Thomas stands beside the kitchen counter, holding his smartphone with his other hand resting near the keys. He wants to make a payment toward his overdue rent, but he is worried about using the grocery money he needs for the week. Reducing the rent balance would be a relief; leaving himself short for food would bring a different worry.
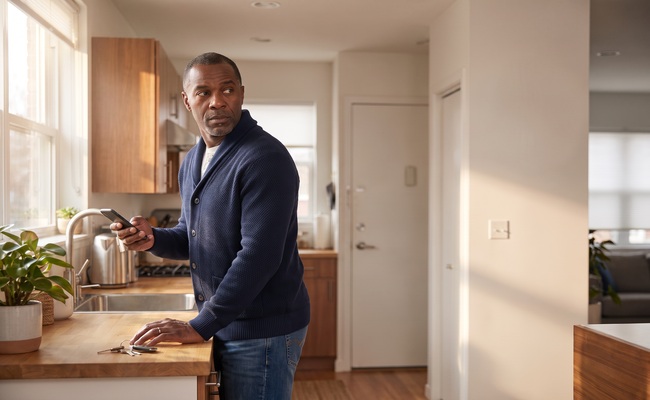
Before choosing an amount, he needs to check the housing deadline and work out what he can offer while keeping food, the next rent payment, and other obligations in view. That means speaking with the landlord and other creditors rather than simply paying whoever sounds most urgent. How can you catch up on rent without ignoring the other debts that still need attention?
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Table of Contents
How to Prioritize Rent and Other Debts
Short answer: Put housing stability and urgent notices first, contact the landlord early, and ask for a written repayment arrangement you can realistically maintain. Apply for assistance at the same time. Protect utilities, food, medication, necessary transportation, and the next rent payment while keeping other obligations on a dated list and contacting creditors about hardship options.
This is a prioritization process, not a rule that rent always overrides every other obligation. Your lease, notices, household needs, account terms, and local law matter. Eviction procedures, response deadlines, eligibility, and protections vary by location. There is no single nationwide eviction deadline to use for your plan.
First: Confirm the Balance and Read Every Notice
Compare the landlord’s current ledger with your lease, receipts, and payment confirmations. Separate unpaid rent from fees and other charges so you can ask about discrepancies without accepting an unexplained total. Record both the arrears balance and the amount and date of the next regular rent payment.
- Read every notice and keep a copy, including any envelope or electronic delivery details.
- Write down any stated response deadline, hearing date, and required action.
- Ask for a written ledger if the balance does not match your records.
- If a notice is unclear or court papers have arrived, seek legal-aid guidance promptly rather than guessing what it means.
Put these dates beside your other bills. A bill calendar can help you see when rent, income, utilities, and creditor payments overlap. Recording a date does not resolve it, but it gives you a concrete basis for deciding which conversation comes first.
Next: Ask the Landlord for a Written Arrangement
Contact the landlord or property manager before the next deadline, even if you cannot pay the full balance. The CFPB’s rent-repayment guidance describes possible options such as adjusted due dates, waived late fees, temporarily lower payments, and repayment plans. These are requests to discuss, not terms a landlord must offer.
A concise request could be: “I’m reviewing the past-due balance and my payment records. I can currently afford [amount] on [date] while covering current rent and essentials. Would you consider a repayment arrangement or timing adjustment? Please send the proposed terms in writing.” Use only amounts and dates supported by your budget.
Before accepting, ask how each payment will be credited, how current rent will be handled, whether fees continue, and what happens if an installment is missed. If a notice or case is already involved, ask what the proposed arrangement means for it and get qualified legal guidance. Do not assume that a partial payment, verbal promise, or assistance application changes a legal deadline.
After a call, send a short written summary and ask the landlord to confirm the agreement. For help keeping a hardship explanation factual and focused, use DSG’s guide to a hardship letter to creditors as a writing aid, not as a substitute for understanding rental terms or local law.
Apply for Assistance Without Waiting
Start searching while you communicate with the landlord. The CFPB’s guide to help paying rent and bills points renters toward local, state, and tribal programs, 211, utility assistance, HUD-approved housing counseling, and legal help. It warns that rental assistance may take several weeks, so do not wait for an application decision before addressing a notice or payment deadline.
- Call 211 and ask about emergency rental assistance, eviction-prevention resources, and legal-aid referrals serving your area.
- Ask each program about current funding, eligibility, required documents, and how to track an application.
- Ask about utility assistance, including the Low Income Home Energy Assistance Program, or LIHEAP, if energy bills are also behind.
- Request a HUD-approved housing counselor who offers rental counseling and can help you navigate the budget, assistance, and referral questions.
USAGov’s emergency rent assistance page also directs renters to 211, state and local programs, and participating housing counselors. Eligibility rules vary by state, and availability is not guaranteed. Keep application confirmations and describe an application as pending unless the program has actually approved it.
If the first program has no funds or cannot help, ask for another referral. Continue landlord communication and seek legal help for urgent notices while you explore those alternatives. Assistance research should run alongside the immediate housing plan, not replace it.
Protect Essentials and Keep Other Debts Visible
Build the plan around dependable income arriving before each due date. List current rent separately from arrears, then include food, medication, utilities, necessary transportation, and required insurance. Calculate what remains before offering an arrears installment. If income arrives unevenly, a paycheck-based budget can help you match available cash to actual dates rather than relying on a monthly total.
Keep other obligations visible, including secured loans, court-ordered payments, taxes, and credit accounts. Do not assume all of them can safely wait or that a housing-first budget changes their terms. Review the consequences and deadlines attached to each, and seek qualified guidance when legal requirements or collateral are involved.
For credit cards, the CFPB recommends contacting the card company promptly, explaining the hardship, stating what you can afford, and asking about available arrangements. Request the terms in writing; do not assume that asking changes the existing payment obligation or guarantees relief.
DSG’s guide to credit card hardship programs can help you prepare that conversation. Keep a record of each creditor’s answer, confirmed terms, and next date. Communicating with creditors is different from silently missing every payment while sending all available cash to rent arrears.
Get Legal Help When Notices or Court Papers Are Involved
If you receive eviction-related notices or court papers, contact legal aid promptly through the routes described in the CFPB rent-and-bills resource or referrals obtained through 211. A HUD-approved housing counselor can help with resource navigation, but questions about your legal rights, court response, or a proposed settlement require qualified legal guidance.
Bring the lease, notices, ledger, payment records, proposed agreement, and assistance application information. Ask what actions and deadlines apply where you live. Procedures and protections differ by location and circumstances; another renter’s experience or an old online rule is not a reliable substitute for checking your situation.
Before signing terms you do not understand, ask for clarification and legal review where appropriate. In particular, do not assume an agreement pauses a case, removes fees, or protects you after a missed installment unless the applicable terms and legal requirements establish that result.
Build and Review a Sustainable Catch-Up Plan
Write the plan as dates, amounts, and actions. Include current rent, each arrears installment, essential expenses, other confirmed payment arrangements, and assistance follow-up dates. Count only income you can reasonably rely on; keep unapproved assistance separate rather than treating it as available cash.
After each payment, save the receipt and check the updated ledger. Review whether the next rent and essentials remain covered. If income changes or assistance is delayed or denied, contact the landlord and affected creditors before the next payment is missed and ask whether revised terms are available.
If the plan works only by leaving every other obligation unaddressed, revisit it. A formal debt-management plan through a credit-counseling organization may help organize eligible debts into one payment, but it does not replace landlord consent, account-specific terms, or legal advice. Not every obligation is covered, and creditors may need to agree to the arrangement. A housing counselor can also help you consider whether the rent remains affordable beyond the catch-up period.
What to Do Today—and if the Plan Falls Short
- Today: read every notice, confirm the rent balance, record deadlines, and list dependable income and essential expenses.
- Next: contact the landlord with a realistic request for written terms, call 211, and start relevant assistance applications.
- In parallel: seek HUD-approved rental counseling, contact other creditors about hardship options, and obtain legal-aid guidance for notices or court papers.
- If the numbers still do not work: ask for revised terms and additional referrals. Do not promise unaffordable installments or wait silently for assistance to resolve an approaching deadline.
The aim is a workable sequence: preserve housing, protect basic needs, pursue help promptly, and keep every important obligation in view. A smaller, confirmed arrangement that fits your cash flow is a better starting point than a promise your budget cannot support.
What to Do Next
Today, read every housing notice, compare the landlord’s ledger with your records, and ask for a written arrangement you can maintain. Start official assistance and legal-aid or housing-counseling routes at the same time, while keeping utilities, food, transportation, taxes, secured debts, and other deadlines visible.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. This article provides general prioritization and resource-navigation guidance for rent arrears and does not determine a reader’s legal rights or eligibility. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.