Yolanda stands beside her car with a repair estimate in her hand, facing the kind of expense that can undo months of careful debt payments. She can send every spare dollar to debt, or keep enough cash available to handle the repair without immediately borrowing again.
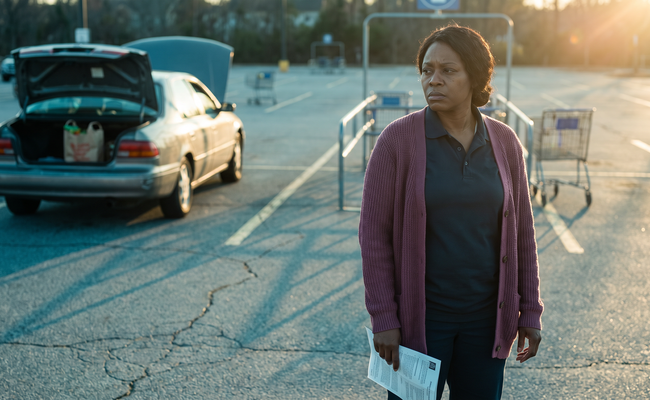
Neither choice feels comfortable when she is trying to owe less and rebuild a cushion at the same time. Rebuilding savings is not abandoning debt repayment; it can protect the progress she has already made. How can you rebuild savings while paying debt without falling behind on either?
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Table of Contents
How to Balance Savings and Debt
Short answer: Protect essential bills and required minimum payments first. Then build a modest cash buffer, set aside money for predictable irregular expenses, and choose an extra-debt payment you can repeat without borrowing for necessities. Automate only what your cash flow can support. As high-cost debt becomes manageable, redirect more money toward savings.
There is no single emergency-fund number that makes this tradeoff right for everyone. A useful starting point is a cushion based on your actual expenses, income stability, and near-term risks—not a target so large that it stops you from starting. The aim is to reduce the chance that one expense forces you back onto a card, while continuing to address expensive debt.
Moving a bill’s due date may ease a timing problem, but it does not create income or reduce the bill. Likewise, a growing savings balance is not progress if you routinely have to borrow for groceries because too much money was transferred out of checking. Build the plan around money that is genuinely available.
Step 1: Protect Essential Bills and Minimum Payments
Before choosing a savings transfer or an extra debt payment, list your take-home income, essential expenses, required debt payments, and due dates. Include housing, utilities, food, necessary transportation, insurance, and health needs. Use a pay-period calendar as well as monthly totals: money arriving later cannot cover a payment due today.
Our guide to a realistic debt repayment budget can help organize those amounts. The first question is not how fast you can repay debt. It is whether the basic plan works without new borrowing.
If you can afford the required minimums, preserve them while rebuilding savings. If essential bills and minimums together exceed your income, do not force a savings transfer or an extra payment. The CFPB’s guidance on what to do when you cannot pay credit card bills recommends adding up income and expenses and contacting the issuer promptly—even before you are behind.
Explain what you can afford, why the usual payment is difficult, and how long you expect the difficulty to last. Ask what assistance is available and how any arrangement affects payments, interest, fees, and account use. Get the terms in writing; help is not guaranteed. A hardship letter to creditors can help you organize the request.
Step 2: Build a Small, Accessible Buffer
Look at the necessary expenses that have disrupted your budget before. Which could happen again soon? What amount could you reasonably set aside without missing essentials or required payments? Choose an initial milestone that offers some protection and is achievable from your current surplus. It does not have to cover every possible emergency.
When you have little or no accessible cash, consider temporarily directing more of that surplus toward the buffer and less toward extra debt payments. This is a tradeoff: leaving a balance outstanding can continue to cost interest, but leaving yourself without cash can make the next urgent expense harder to handle. Reassess rather than following a rigid savings-first rule.
Keep the buffer separate enough from everyday spending to recognize its purpose, but accessible when needed. Before choosing an account, check fees, minimum-balance requirements, withdrawal restrictions, and transfer times. Do not assume transfers between accounts are instant.
This buffer is liquid cash for near-term needs, not retirement savings and not unused credit. Do not count retirement investments as though they were money freely available for next week’s expense. This plan is not a recommendation to stop retirement contributions, withdraw retirement funds, or change investments; those decisions require a separate review.
Step 3: Plan for Irregular Expenses
An expense can be irregular without being unexpected. Insurance renewals, routine vehicle maintenance, annual fees, and seasonal costs belong in the budget even if they do not arrive every month. Review past transactions and upcoming bills so these costs do not keep emptying the emergency buffer.
For each known expense, write down its expected amount, due date, and what you have already reserved. Divide the remaining amount across the pay periods left before it is due. Update estimates when you receive a bill or quote. Keep these earmarked amounts distinct from emergency savings, even if you track them within the same account.
If there is not enough time to save the full amount, reduce discretionary spending or extra debt payments where possible. Ask the provider about available payment arrangements before the bill becomes overdue, and check any fees or total-cost changes. Do not assume a payment plan is free or available.
For a serious emergency or disaster, the CFPB’s financial recovery guidance explains steps such as contacting lenders, documenting conversations, and checking relevant insurance or assistance options. Those actions may help you understand the amount you must cover before committing your savings.
Step 4: Choose a Sustainable Extra-Debt Amount
After essentials, minimums, near-term irregular expenses, and your planned buffer contribution, identify what remains. That is the starting point for an extra debt payment—not the balance your banking app shows before pending bills clear.
Choose an amount you can repeat through an ordinary, less-than-perfect month. If income varies, use a conservative baseline and make additional payments only after money arrives and upcoming needs are covered. You can split the remaining surplus between savings and debt; there is no required percentage.
Our guide to which debts to pay first can help you think through the repayment order. The comparison of debt snowball and debt avalanche methods offers another way to organize extra payments. Neither approach substitutes for protecting essentials and maintaining required payments on the other accounts.
Before using a one-time payment for debt, check whether your buffer needs replenishing or an irregular bill is approaching. Allocate money you actually receive, rather than promising a future refund, bonus, or extra paycheck to several purposes at once.
Step 5: Automate Carefully, Not Blindly
Automation can make the plan easier to follow, but a transfer is useful only if the account can support it. Start with an amount that fits your cash-flow calendar. Schedule it after you have confirmed income is available, accounting for pending transactions and bills due before the next payday.
Turn on available low-balance alerts and review the first transfers. If your income is unpredictable, a manual transfer after each deposit may be safer than a fixed recurring amount. Pause or reduce transfers when hours fall, a bill changes, or the buffer must cover an urgent expense.
The CFPB’s guide to overdraft options explains why transaction timing and account terms matter. Opting out of debit-card and ATM overdraft coverage does not eliminate every risk associated with checks or recurring electronic payments. Linking savings may help with some shortfalls, but check the terms and remember that a transfer can use up your emergency money.
Do not assume automatic debt payments and automatic savings transfers coordinate with each other. Review both schedules. If a transfer leaves checking too low for a required payment, adjust the transfer rather than hoping the account will cover it.
Step 6: Increase Savings as High-Cost Debt Comes Under Control
Review the plan when a high-cost balance is paid off or its payment becomes more manageable. If that frees up money, give it a job before it disappears into everyday spending: replenish the buffer, prepare for known expenses, or increase your broader emergency savings contribution.
Expand your savings target based on essential expenses, income reliability, household responsibilities, and likely risks. A starter buffer and a longer-term emergency reserve serve different stages of the plan. Reaching the first milestone does not mean your household is protected from a prolonged income interruption.
If you need to use the buffer, treat that as a reason to rebalance—not as proof that saving failed. Confirm the remaining balance, protect upcoming essentials and minimums, and consider reducing extra debt payments temporarily while you rebuild. There is no guaranteed recovery timeline.
Before draining savings for a final payment, work through the tradeoffs in using an emergency fund to pay off debt. A smaller debt balance matters, but so does having enough accessible cash to avoid immediately borrowing again.
Your First Review: Put the Plan Into Motion
- Map income, essential bills, minimum payments, and pending transactions through your next pay period.
- Contact any creditor whose required payment is unaffordable before committing money to savings or extra repayment.
- Choose an initial cash-buffer milestone and identify where the money will remain accessible.
- List known irregular expenses and reserve what you can toward their due dates.
- Set a repeatable extra-debt amount and a savings contribution that leave room for upcoming needs.
- Review the results after the next pay cycle before increasing either amount or making transfers automatic.
The goal is not to make both balances move dramatically every month. It is to build a routine that pays what is due, anticipates ordinary costs, and leaves you less exposed when something goes wrong.
Frequently Asked Questions
Should I stop extra debt payments until I have savings?
Not automatically. If you have no accessible cash, temporarily shifting some surplus toward a small buffer may make sense. Weigh the debt’s cost against upcoming needs and the risk of borrowing again. Keep required payments current when affordable; if they are not, contact creditors rather than treating the shortfall as an extra-payment decision.
What if nothing is left to save?
Start with the shortfall, not an automatic transfer. Check expenses, payment timing, and whether a creditor offers affordable assistance. A due-date change can help timing but cannot fix expenses that exceed income. The CFPB also suggests considering nonprofit credit counseling when credit card payments are difficult. Our guide to credit counseling versus debt settlement explains why those services should not be treated as interchangeable.
Does available credit count as an emergency fund?
No. Available credit is borrowing capacity, not cash you have saved. Using it creates a repayment obligation under the account’s terms. Keep track of accessible savings separately so your plan does not depend on taking on another balance.
How do I decide whether to use the buffer?
What to Do Next
Ask whether the expense is necessary, whether waiting could threaten health, housing, safety, or necessary transportation, and whether another affordable option exists. Predictable bills should have their own reserves where possible. A necessary expense does not have to be dramatic to justify using savings; afterward, adjust the plan to rebuild what you used.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. This article explains general savings-and-debt tradeoffs and is not an individualized budget or investment plan. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.