David has enough money to cover some of the bills spread across the counter, but not enough to make every deadline disappear. The choice is uncomfortable: pay the wrong obligation first and an essential need could be left exposed.
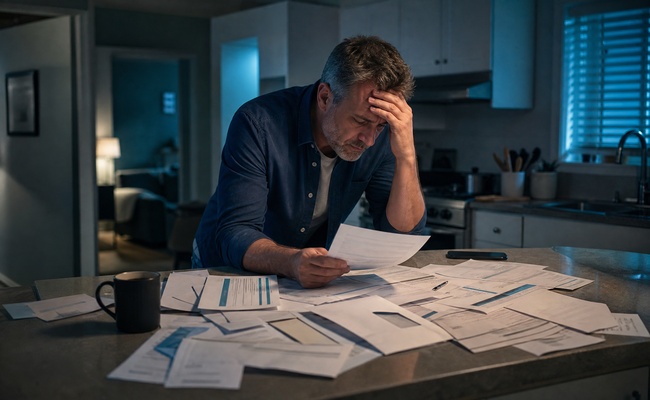
He cannot solve the problem by choosing the balance that looks most intimidating. He needs to sort the bills by essential needs, deadlines, and consequences. Which debts and bills should come first when there is not enough money for everything?
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Table of Contents
The Priority Debt Checklist
Short answer: Start by protecting housing, essential utilities, food, health and safety, and transportation or other needs that enable income. Review court, tax, support, and secured-debt notices promptly and follow their instructions and deadlines. Then plan payments toward unsecured debts and, if money remains, extra debt reduction.
This is a household planning framework, not a universal legal payment order. Exact consequences and priority rules depend on the debt, contract, court order, and jurisdiction. An urgent notice can change what needs attention today, even if that account would otherwise sit lower on your checklist.
- Identify the money actually available before your next income arrives.
- Reserve money for essential living needs during that period.
- Separate notices and court orders from ordinary bills; check dates and required actions.
- Contact any biller you cannot pay as agreed and ask about a workable arrangement.
- Decide what is available for other required payments before choosing extra-paydown targets.
The CFPB’s Your Money, Your Goals toolkit supports this approach through bill calendars, cash-flow budgeting, and prioritizing bills when cash is short. Use its planning tools rather than its historical numerical examples.
First: Protect Essential Needs
Not every essential expense is a debt. Groceries, necessary medication, and transportation still need a place in the plan before you decide how much to send to creditors. Start with what your household needs to remain housed, safe, and able to function until the next income date.
- Housing: identify the rent or mortgage amount due, any arrears, and any notice requiring action. If you cannot pay, contact the landlord, property manager, or lender promptly and keep a written record.
- Essential utilities: identify the electricity, heat, water, or other services needed for health and safety. Ask the provider about payment arrangements and any applicable shutoff-protection process.
- Food, health, and safety: reserve a realistic amount for food, necessary treatment or medication, and immediate household safety needs. Distinguish current care needs from older medical bills.
- Transportation and income-enabling needs: identify what you need to keep earning income, such as necessary transport, childcare, or essential phone service. Consider actual alternatives rather than automatically ranking every vehicle or service payment the same way.
If rent is already at risk, USAGov’s emergency rent assistance guide points to state and local programs, 211, and HUD-participating housing counselors. Contact the landlord or property manager in writing, preserve notices, and seek local legal aid or housing counseling promptly. Program rules vary; there is no single nationwide eviction deadline or guaranteed assistance.
For utility trouble, USAGov’s utility assistance guide identifies energy assistance resources, including LIHEAP, and qualifying phone or internet assistance through Lifeline. Contact both the provider and relevant assistance program rather than assuming an application will change a shutoff date.
Once you have estimated these needs, put them into a realistic debt repayment budget. If essentials already exceed available income, the immediate task is to seek arrangements and support—not to force an extra debt payment into the budget.
Next: Review Notices, Orders, and Secured Debts
Review court papers, tax notices, support orders, and secured-debt notices alongside your essential-needs plan, not only after every essential bill is fully paid. Payment priority and response priority are different: a document may require a response or professional advice even when you cannot afford a payment.
- Find the stated deadline, required action, contact information, and account or case reference.
- Check the notice against your records and the relevant agreement or order.
- Ask the issuer of the notice what options exist and what any proposed arrangement would change.
- Seek qualified legal or tax help when instructions, consequences, or competing obligations are unclear.
For a loan secured by property, review the agreement and any notice to understand what property is involved and what action is requested. A housing or vehicle loan may also belong in your essential-needs plan. Do not assume that every secured debt has the same urgency or that one missed payment produces an automatic legal result.
Likewise, do not assign all tax or support obligations a fixed position based only on the category name. Follow the applicable notice or order and obtain situation-specific help. If your paperwork concerns earnings deductions, the DSG guide to addressing wage garnishment offers related reading; verify applicable legal details with a qualified professional.
Then: Address Unsecured Debts and Extra Payments
After accounting for essential needs and urgent notices, review credit cards, unsecured personal loans, older medical bills, and other unsecured balances. Check each account’s required payment, due date, written terms, and any correspondence. Do not assume an unsecured debt is consequence-free, or that every medical or family debt automatically belongs at the bottom.
If you cannot make a credit card minimum, the CFPB recommends contacting the card company right away. Explain why you cannot pay the minimum, what you can afford, when normal payments might restart, and the specific temporary payment amount or period you are requesting.
Ask what any proposed arrangement means for your required payments and account terms, and request written confirmation. If you owe a friend or relative, use the same practical approach: explain what is affordable, review the existing agreement, and record any agreed changes. Do not promise a repayment date that your cash-flow plan cannot support.
Extra payments are a separate decision from handling this week’s essentials and deadlines. Once those are addressed, you can compare interest rates, balances, and the payment routine you can sustain. Our guide to debt snowball and debt avalanche approaches can help you compare options; neither method replaces a review of urgent obligations.
Before committing all remaining cash to extra payments, also consider upcoming essential expenses and your available cushion. The DSG discussion of using an emergency fund to pay off debt can help frame that tradeoff. There is no single extra-payment amount that fits every household.
Build Your Own Payment Checklist
Use one page or spreadsheet to connect the bills with the money available. Include living expenses as well as debts so that the list reflects what your household actually needs.
- Record available cash and expected income dates. Separate predictable income from uncertain or one-time amounts.
- List each expense or debt, the amount due, its due date, and any past-due amount.
- Mark what it protects: housing, utilities, food, health, safety, or the ability to earn income.
- Add notices and orders, with their response deadlines and the next action required.
- Choose an action for each item: pay, contact the biller, request assistance, verify records, or obtain professional advice.
- Record arrangements and confirmations, then update the list when income, expenses, or notices change.
A bill that matters most overall may not be the next bill due. Map the dates as well as the categories, and reserve money for essential bills that arrive later. Recheck the plan whenever income comes in or new paperwork arrives rather than treating the first ranking as permanent.
When There Still Is Not Enough Money
A priority checklist cannot make an unaffordable set of bills affordable. If the numbers still do not work, use the shortfall to guide your calls: state what is available, ask for a specific arrangement, and seek official housing or utility assistance where relevant. Keep copies of notices and notes of conversations.
If a biller declines your request, ask whether another assistance or review process is available. For urgent housing or legal paperwork, seek local legal aid or housing counseling rather than assuming a payment request has paused the deadline. For several unaffordable credit card accounts, the CFPB notes that credit counseling may help.
Our guide to credit counseling versus debt settlement provides context for comparing help. The CFPB identifies promises of results, upfront-fee demands, and instructions to stop communicating with creditors or stop making minimum payments as debt-relief warning signs.
Your next step is to list the money available before your next income date, reserve essential living costs, and identify the first notice or bill that needs action. Pay what your plan supports, contact those you cannot pay, and revise the checklist as you receive answers. The goal is a workable sequence of actions—not a rigid ranking that ignores your circumstances.
What to Do Next
Before the next income date, list available cash, essential living costs, notices or orders requiring action, and the bills you cannot pay. Protect basic needs, contact affected providers, preserve written records, and revise the checklist as you receive answers rather than following a rigid ranking.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. this article provides a general framework for deciding which bills and debts need attention first. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.