Patricia opened a Form 1099-C after finally settling a credit-card balance and felt the relief leave the room. She had planned to use her remaining savings for groceries and the mortgage, not another tax bill. The question was not whether the debt had been canceled; it was whether, immediately before cancellation, her debts exceeded the value of everything she owned.
That question is the starting point for the IRS insolvency worksheet. The calculation can help establish whether some or all of canceled debt qualifies for exclusion from federal taxable income, but a settlement alone does not establish eligibility. You need the right financial snapshot, supportable values, and correct reporting on Form 982. Here is how to put those pieces together without confusing debt relief with a guaranteed tax-free result.
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Quick Answer
Short answer: Use the insolvency worksheet in IRS Publication 4681 to compare your total liabilities with the fair market value of your total assets immediately before the debt cancellation. If liabilities exceed assets, the difference is your insolvency amount. Under the insolvency exclusion, you generally cannot exclude more canceled debt than that amount. Include retirement accounts and other assets protected from creditors, and list property at its full value while recording secured loans separately as liabilities. When claiming this exclusion, complete Form 982 with your federal return, review any required tax-attribute reductions, and keep the worksheet and supporting records rather than routinely attaching the worksheet.
Table of Contents
What the insolvency worksheet does—and how Form 982 fits
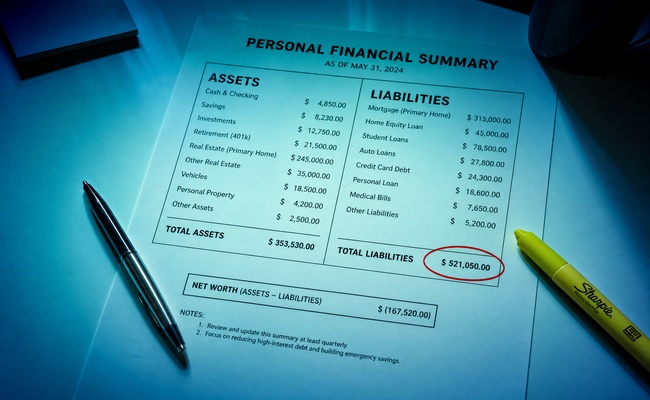
The IRS insolvency worksheet answers a specific question: immediately before a debt was canceled, did your total liabilities exceed the fair market value of all your assets? If so, the difference is your insolvency amount. That amount limits how much canceled debt you can exclude under the federal insolvency rule.
The worksheet appears in IRS Publication 4681. Form 982 serves a different purpose: you attach it to your federal income-tax return to claim the applicable exclusion and address required reductions to tax attributes. You generally keep the worksheet as supporting documentation.
Being unable to make monthly payments is not the same as being insolvent for tax purposes. A person can have serious cash-flow problems but still own assets worth more than their debts. If you need the broader explanation first, see our guide to taxes on settled debt and Form 1099-C.
Important caution
The biggest errors are using year-end balances instead of the cancellation-time figures, omitting retirement accounts, and counting only home equity while also subtracting the mortgage as a liability. Do not deliberately undervalue property or add unsupported obligations to increase the exclusion. A Form 1099-C does not establish that every reported dollar is taxable, but financial hardship does not automatically make it excludable either. Nonrecourse loans, joint ownership, multiple cancellations, and bankruptcy can change the analysis. Excluding income may also require tax-attribute reductions, so a completed worksheet is not the end of the filing process.
Confirm the cancellation and use the right financial moment
Save your Form 1099-C, settlement agreement, creditor correspondence, and payment records. Compare the debtor information, reported amount, and date with those documents. If something appears wrong, ask the creditor for an explanation and, where appropriate, a corrected form.
The required snapshot is immediately before the cancellation—not automatically the previous calendar day, the settlement-payment date, December 31, or the date you received the form. A prior day’s statement may help establish a balance, but account for material transactions before the cancellation. If the actual cancellation timing is uncertain, get help reconciling the records.
- Collect bank and investment statements covering the relevant time.
- Obtain loan balances and unpaid account balances as of that time.
- Gather evidence of property values, including any ownership percentages.
- Record the cancellation amount separately from the total debts you owed.
For separate cancellation events, do not assume one year-end worksheet covers them all. Your financial position may change between events, so separate calculations may be needed.
List assets at fair market value, not just equity
Fair market value generally means what a willing buyer would pay a willing seller under ordinary market conditions. Use values appropriate to the cancellation time, not original purchase prices, replacement costs, or today’s prices if the cancellation happened earlier.
Follow the worksheet’s asset categories and include property even if it is protected from creditors. Common assets include:
- Cash, checking accounts, savings accounts, and certificates of deposit.
- Stocks, bonds, and other investments.
- Retirement accounts, including 401(k) accounts and IRAs.
- Real estate and vehicles at their full fair market values.
- Household goods, electronics, jewelry, and collectibles at reasonable resale values.
- Life insurance cash value, business interests, and other property you own.
Do not enter only your home equity if you are also listing the mortgage as a liability. For example, a home worth $180,000 with a $170,000 mortgage is generally entered as a $180,000 asset and a $170,000 liability—not a $10,000 asset plus a $170,000 liability. Apply the same separate-value approach to a financed vehicle.
Joint ownership requires care. Determine whose debt was canceled and what assets and liabilities belong in that person’s calculation. Do not automatically include or exclude a spouse’s property solely because you file a joint return. Ownership rules and the facts can require professional review.
List liabilities without counting the canceled debt twice
List the liabilities you actually owed immediately before the cancellation. Typical categories include mortgages, home-equity loans, auto loans, student loans, credit card balances, unpaid medical bills, personal loans, and tax debts. Use the outstanding amounts, not monthly payments or credit limits.
Include the debt being canceled because it still existed immediately before the cancellation. However, include it only once. If you already listed that account’s entire balance, do not add the Form 1099-C amount again as a separate liability. The account balance before cancellation and the amount ultimately canceled may not be identical.
- Check statements for balances that changed after a settlement payment.
- Do not treat future living expenses as existing debts.
- Include family loans only when they are genuine, supportable obligations—not gifts or informal expectations.
- Do not assume a credit report lists every debt or gives the correct historical balance.
Special rules apply to nonrecourse debt, where the lender’s recovery is limited to specified collateral. Contingent obligations, disputed balances, and guarantees also need careful analysis. Use Publication 4681 and qualified help rather than adding every possible obligation mechanically.
Keep the facts separate
The IRS does publish an Insolvency Worksheet in Publication 4681; it is a supporting calculation, not a separately filed tax form. Form 982 is the form used to report the relevant exclusion and tax-attribute reductions. Also, the $600 threshold generally concerns Form 1099-C reporting by covered creditors, not whether canceled debt can be taxable. You may need to address a cancellation even without receiving that form. Conversely, a form with an incorrect amount, date, or debtor information should be investigated rather than accepted without question. State income-tax treatment may differ from federal treatment.
Calculate the maximum insolvency exclusion
Subtract total assets from total liabilities. If the result is positive, that is your insolvency amount. If assets equal or exceed liabilities, there is no exclusion under the insolvency rule, although another exception or exclusion may still apply.
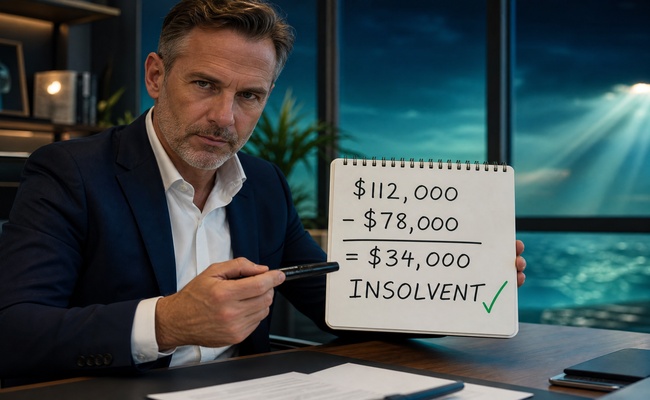
For a straightforward cancellation eligible for the insolvency exclusion, the excluded amount cannot exceed either the qualifying canceled debt or your insolvency amount. These illustrative examples show the difference:
- Full exclusion: liabilities of $112,000 minus assets of $78,000 produce $34,000 of insolvency. A qualifying $19,400 cancellation falls within that limit.
- Partial exclusion: $8,000 of insolvency against $15,000 of qualifying canceled debt permits an $8,000 insolvency exclusion. The remaining $7,000 is generally taxable unless another applicable rule excludes or excepts it.
- No insolvency exclusion: assets of $90,000 against liabilities of $85,000 do not establish insolvency.
A full exclusion of the canceled debt does not mean your entire tax return has no balance due. It also does not eliminate the need to consider tax-attribute reductions or state tax treatment.
Check valuations and other rules that could change the result
Before relying on the total, review both omissions and assumptions. A retirement account you cannot readily access still generally belongs in the asset calculation. Likewise, bankruptcy protection for an asset does not automatically remove it from the insolvency worksheet.
For a vehicle, keep evidence that reflects its age, mileage, condition, and local market at the relevant time. A valuation guide or comparable listings can support an estimate, but no single website guarantees the correct value. For household goods, use realistic resale values. Do not simply choose the lowest available number to enlarge the exclusion.
Different cancellation rules may apply before or instead of insolvency. Debt discharged in a qualifying title 11 bankruptcy can fall under a separate exclusion. The IRS bankruptcy guidance explains that bankruptcy also creates specific tax and reporting issues. Our comparison of bankruptcy versus debt settlement provides broader decision context, but it does not determine your tax treatment.
Do not assume that a mortgage, student loan, or business debt qualifies because a similar cancellation received favorable treatment in another year. Eligibility can depend on the debt type, the facts, and the law for the cancellation year.
Complete Form 982 and review tax-attribute reductions
Use the IRS Form 982 page to obtain the form and consult the Form 982 instructions for the tax year involved. Attach the completed form to the federal return for the year in which the cancellation must be reported.
- If insolvency is the exclusion you are claiming, check the applicable box on line 1b.
- Enter the amount excluded on line 2. If you have multiple exclusions or cancellation events, review how the form combines them.
- Review Part II and the instructions for required tax-attribute reductions.
- Report any remaining taxable cancellation-of-debt income on the appropriate income line. Nonbusiness canceled debt is generally reported on Schedule 1 of Form 1040.
Tax attributes include items such as loss carryovers, credit carryovers, and the tax basis of property. An exclusion can require reducing these benefits, and Part II may matter even if you do not own a business. A basis reduction can affect the taxable gain on a later sale.
Do not assume Part II should be blank just because the entire cancellation was excluded. The ordering, limits, and timing of reductions can be technical. A CPA or enrolled agent can review both the worksheet and the complete Form 982; reviewing only the subtraction leaves an important part of the return unchecked.
Keep a record file that explains every number
Your worksheet should tell a reviewer what happened, when it happened, and how you determined each amount. Generally, you do not attach the worksheet or all supporting statements to the return unless the IRS requests them or applicable filing instructions require additional information.
- Keep the completed worksheet labeled with the cancellation event and relevant date.
- Save Form 1099-C, the settlement agreement, and cancellation correspondence.
- Match bank, retirement, investment, and loan records to the worksheet entries.
- Save dated valuation evidence and explain adjustments for property condition or ownership.
- Retain the filed return, Form 982, and any calculations of tax-attribute reductions.
If an exact historical statement is unavailable, document the evidence and method used to reconstruct the balance. An unsupported guess is weaker than a reasonable estimate with a clear explanation.
There is no universal seven-year retention rule specifically for insolvency worksheets. The IRS record-retention guidance generally calls for three years in ordinary income-tax situations, with longer periods for certain circumstances. Records affecting property basis or later returns may need to be kept much longer. Ask your preparer which records have continuing tax significance.
Respond to IRS questions and correct mistakes carefully
If the IRS sends a notice, read what it actually requests and note the response deadline. A notice does not by itself establish that your exclusion was wrong. It also does not guarantee that submitting a worksheet will resolve the issue.
Respond through the method specified in the notice. Provide the requested worksheet and supporting records, with a concise explanation connecting the cancellation amount, insolvency calculation, and Form 982 entries. Keep a copy of everything you submit and evidence of delivery when available.
If you discover an error after filing, determine whether an amended return is needed. Form 1040-X and a corrected Form 982 may be appropriate, but an open notice or examination can affect how you should proceed. A tax professional can help coordinate the correction. Fixing an error does not automatically eliminate tax, interest, or penalties.
For another account you have not yet resolved, estimate the potential tax effect before negotiating a debt settlement. A debt management plan generally aims to repay principal rather than cancel it, but the creditor’s actual terms determine whether any cancellation occurs. The useful comparison is the full cost and obligations of each option—not simply the size of the reduced payment.
Frequently Asked Questions
Is the insolvency worksheet an official IRS form?
The IRS publishes an Insolvency Worksheet in Publication 4681, but it is not a separately filed tax form. You generally retain it as support for the exclusion reported on Form 982, which is attached to your federal return.
Do I include my 401(k) or IRA as an asset?
Yes. Retirement accounts generally count as assets for the insolvency calculation even when protected from creditors or difficult to access. Do not omit them simply because withdrawing the money could create taxes or penalties.
What happens if I am only partially insolvent?
The insolvency exclusion is limited to your insolvency amount immediately before cancellation. If you have $8,000 of insolvency and $15,000 of qualifying canceled debt, $8,000 can be excluded under this rule. The remaining $7,000 is generally taxable unless another exception or exclusion applies.
Can I prepare the worksheet and Form 982 myself?
You can prepare a straightforward calculation using IRS Publication 4681 and the Form 982 instructions. Professional review is especially useful for joint ownership, multiple cancellations, nonrecourse loans, uncertain dates, bankruptcy, or tax-attribute reductions. Completing the worksheet does not automatically complete Form 982.
How long should I keep the worksheet and supporting records?
Keep them for the applicable IRS record-retention period, generally three years for ordinary income-tax records, with longer periods in some circumstances. Records supporting basis adjustments, carryovers, or other items affecting later returns may need to be retained longer. There is no universal seven-year rule specifically for insolvency worksheets.
Can canceled debt be taxable if I never receive Form 1099-C?
Yes. The absence of Form 1099-C does not determine whether canceled debt must be reported. The $600 threshold generally concerns reporting by covered creditors, not a tax-free allowance. Review the cancellation itself and any applicable exceptions or exclusions.
What to Do Next
Start by saving the settlement agreement, Form 1099-C, and any cancellation letter. Confirm when the cancellation occurred, then gather account balances and reasonable property values for immediately before that event. Complete the asset and liability lists, check for double counting, and calculate the possible exclusion. Use the IRS instructions for the tax year involved to prepare Form 982 and report any remaining taxable amount. Before filing, consider a CPA or enrolled agent review if ownership, loan terms, tax attributes, or the cancellation date are unclear. Keep a dated worksheet and an organized evidence file explaining every material number.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Tax treatment of canceled debt and the use of Form 982 depend on the debt, the insolvency calculation, and current IRS rules. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.
References and Sources
- IRS — About Form 982: Official source — Form 982 is used to report qualifying discharge-of-indebtedness exclusions and reductions of tax attributes.
- IRS — Publication 4681, Canceled Debts, Foreclosures, Repossessions, and Abandonments: Official source — Provides the Insolvency Worksheet, the immediately-before-cancellation test, asset and liability guidance, exclusion limits, and special rules for bankruptcy and nonrecourse debt.
- IRS — Instructions for Form 982: Official source — Supports Form 982 line 1b and line 2 reporting, required tax-attribute reductions, and the need to review Part II and applicable instructions.
- IRS — Topic No. 431, Canceled Debt: Official source — Explains the general canceled-debt income rule, Form 1099-C reporting, creditor contact for incorrect information, exceptions and exclusions, and reporting without a received form.
- IRS — Declaring Bankruptcy: Official source — Supports the distinction between qualifying bankruptcy treatment and the insolvency exclusion, including bankruptcy-related tax reporting considerations.
- IRS — How Long Should I Keep Records?: Official source — Supports ordinary three-year record retention, circumstances requiring longer retention, and continued retention of records affecting property basis.