Rowena dispatched school buses for twenty-two years, which is a job made entirely of numbers that have to be right the first time. To challenge an incorrect judgment, start by comparing the amount and parties with the court record. So when the notice from the court arrived and the amount printed on it read $9,340, she knew something was wrong before she could have explained why. The debt had been $4,930. She had written that figure on a legal pad the night the first collection letter came, and she had looked at it often enough since to know it by heart.
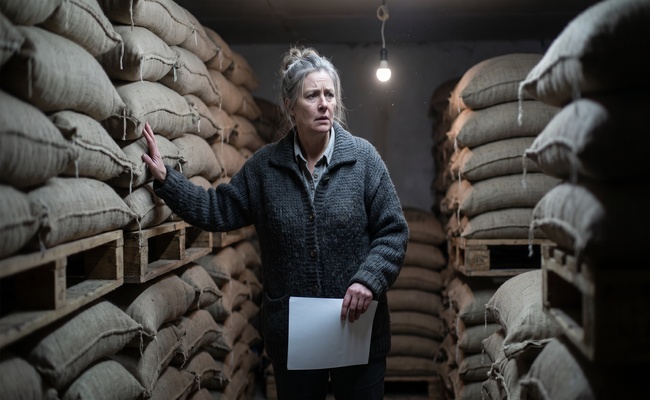
She read the notice standing in the back room of the seed and feed store where she worked three mornings a week, sacks stacked past her shoulders and one bulb burning overhead, holding the page face down against her leg between glances as though not looking at it might change what it said. Two digits had been reversed. Somebody had typed 9,340 where 4,930 belonged, and a clerk had entered judgment for that number because a sworn affidavit said it was owed.
Rowena assumed the mistake would be obvious to anyone who looked. What she learned instead is that the court does not go looking, that nothing in the system notices a transposition on its own, and that the wrong number becomes the amount she legally owes until she does something specific about it.
She also learned the thing almost nobody is told. The route available to challenge an incorrect judgment in her situation had no deadline on it at all, while the routes she had been warned about did. Learning how to challenge an incorrect judgment turned out to depend far less on being right than on matching the right kind of objection to the right kind of error.
At The Debt Survival Guide, our team draws on over 45 years of CPA experience to help people evaluate difficult financial decisions with clarity and caution. We understand that the need to challenge an incorrect judgment feels like something a court should catch by itself, and that it never is. This guide explains how to read what the judgment says, why clerical and substantive errors follow different clocks, which grounds exist, how to file in time, why filing alone does not stop collection, and what winning actually produces. Because state court rules and individual circumstances vary widely, educational information cannot replace individualized legal or financial advice.
Table of Contents
How Do You Challenge an Incorrect Judgment After It Has Been Entered?
You challenge an incorrect judgment by filing a motion in the same court that entered it, asking the judge either to correct the judgment or to set it aside. Which of those two you request is the first decision and the most important one, because each follows a separate rule and a separate clock.
Where the problem is a clerical mistake, the federal model treats it as a correction. Under the federal Rule 60 model, a federal court may correct a clerical mistake or one arising from oversight or omission; in state court, the applicable state rule, court, and deadline control whenever one is found in a judgment, order, or other part of the record. No time limit appears in that provision, and the court may act on its own motion.
Where the problem is substantive, the way to challenge an incorrect judgment is to ask that it be set aside, and the same rule lists the grounds: mistake or excusable neglect, newly discovered evidence, fraud or misrepresentation by the opposing party, a judgment that is void, a judgment already satisfied or discharged, and any other reason justifying relief. Some carry a one-year outer limit and some do not.
Two cautions belong to any attempt to challenge an incorrect judgment. Filing pauses nothing, because the rule states that the motion does not suspend the judgment’s operation, so a garnishment already running keeps running. Every deadline named here is federal-model guidance rather than a substitute for the state-court rule, local procedure, or actual notice governing the judgment.
1. Read What the Judgment Actually Says Before You Object to Any of It
Almost every failed attempt to challenge an incorrect judgment begins the same way, with a person who is certain something is wrong and cannot say precisely what. Courts do not act on certainty. They act on identified errors, and identifying one means reading the document rather than reacting to it.
Anyone preparing to challenge an incorrect judgment should start with the four items that determine everything downstream: the case number, the name of the party the judgment was entered against, the amount, and the date of entry. Copy them onto a single sheet exactly as they appear, including the parts that look wrong.
Then find the papers the judgment was built on. A judgment for a specific sum usually rests on an affidavit stating that amount, and under the federal rule governing default judgments a clerk may enter judgment for a sum certain on the plaintiff’s request with an affidavit showing what is due. Nobody weighed evidence. Someone swore to a figure and the figure was entered, which is exactly how a transposition survives all the way to a court order.
Compare that figure against your own record. If you kept the validation notice the collector was required to send, you are holding a document that itemizes the amount as of a date certain, reflecting interest, fees, payments, and credits. That itemization is the single most useful piece of paper a reader can bring to a motion to challenge an incorrect judgment, because it comes from the collector rather than from you.
Write the discrepancy as one sentence: the judgment says one number, the record says another, here is the difference. A reader who can produce that sentence is ready to challenge an incorrect judgment. A reader who cannot is not ready, and filing early does not help.
2. Separate a Clerical Error From a Substantive One, Because the Clocks Are Nothing Alike
This distinction decides whether a reader still has options, and it is the one popular guidance flattens most often. The advice you will hear everywhere is that you have one year to challenge an incorrect judgment. That is wrong in both directions, and the difference is worth real money.
A clerical error is a typing, arithmetic, or transcription problem: a transposed figure, a misspelled name, a total that does not match the sum of its parts, a docket entry recording something other than what the judge ruled. Under the federal model the court may correct that kind of mistake whenever it is found. Not within a year. Whenever. The provision reaches the judgment, the order, and any other part of the record.
Rowena’s judgment is that kind of problem. Nothing about her case was decided incorrectly. A number was typed wrong and the wrong number was entered, so her route to challenge an incorrect judgment does not expire, and the year she spent believing she was too late cost her nothing but the year.
A substantive error demands a different way to challenge an incorrect judgment, because it means the judgment reflects a decision that should not have been made: you were never served, the debt was not yours, it was already paid, it was discharged in bankruptcy, or the other side misrepresented something material. Those require setting the judgment aside rather than correcting it, and that is where the one-year figure comes from.
Here is the part almost nobody states correctly. Under the federal rule the one-year outer limit applies to exactly three grounds: mistake or excusable neglect, newly discovered evidence, and fraud or misrepresentation. The remaining grounds, including a void judgment and one already satisfied or discharged, carry no one-year cap. They require only that the motion be made within a reasonable time.
The consequence is large. A reader who was never properly served, or whose debt was wiped out in bankruptcy, has not automatically lost the right to challenge an incorrect judgment on day 366. Anyone told otherwise was told something the rule does not say.
3. Identify the Ground That Actually Fits Your Situation
Motions to challenge an incorrect judgment are granted on grounds, not on grievances. The most common reason an attempt to challenge an incorrect judgment fails is that the filing describes unfairness in general terms without naming the specific basis the rule recognizes.
The federal model recognizes six grounds on which to challenge an incorrect judgment. Read them as a list of doors rather than as legal theory, and find the one your facts already open.
Mistake, inadvertence, surprise, or excusable neglect. A missed hearing you had a real reason to miss, or a genuine misunderstanding about what was required. One-year limit applies.
Newly discovered evidence. Evidence that reasonable diligence could not have turned up in time. One-year limit applies.
Fraud, misrepresentation, or misconduct by the opposing party. A sworn amount the other side knew was wrong belongs here. One-year limit applies. Where a collector’s conduct is part of the picture, the Fair Debt Collection Practices Act may also be relevant to what was done in pursuit of the debt.
The judgment is void. The strongest ground available to most readers and the one most often overlooked. A judgment entered without proper service is the standard example. No one-year cap.
The judgment has been satisfied, released, or discharged. A debt paid before the case was filed, wiped out in bankruptcy, or resting on an earlier judgment since reversed. No one-year cap, and badly under-known.
Any other reason that justifies relief. A genuine catch-all, and a weak opening position when a specific ground fits.
One limitation deserves stating plainly, because it is why this article names no state grounds. The federal rule’s own drafters wrote that the provision does not define the substantive law on grounds for vacating judgments and merely prescribes the practice. Even the federal rule declines to say what counts, so anyone preparing to challenge an incorrect judgment must find their own state’s grounds, and the clerk of the court that entered it can say where they are published. The Consumer Financial Protection Bureau’s debt collection resources are a useful orientation to the surrounding process.
4. File in the Right Court Before the Clock You Are Actually Under Closes
A motion to challenge an incorrect judgment goes to the court that entered it. Not to the collector, not to the collection agency’s attorney, not to a courthouse that is closer. A reader who writes to the law firm instead of filing with the court has not begun to challenge an incorrect judgment, however firmly the letter was worded.
Ask the clerk of that court two questions, both of which clerks answer routinely: what motion is used to correct or set aside a judgment here, and what deadline applies to the ground being raised. Clerks cannot give legal advice and can tell you what the local rule and local form are, which is what you need.
Then write the motion to challenge an incorrect judgment around the identified error rather than around the story. State what the judgment says, state what the record shows, state which ground applies, and attach the documents proving the gap. Rowena’s motion is two paragraphs and one exhibit.
Where the judgment was entered by default, one distinction changes the odds sharply. Under the federal model a court may set aside an entry of default for good cause, a comparatively low bar, while a final default judgment is set aside only under the demanding standard governing substantive relief. The gap between those two is often days, which is why a reader intending to challenge an incorrect judgment should file sooner rather than better-prepared-later.
Anyone who has been served and has not yet had judgment entered is in a far stronger position than they will be next week. If that describes you, our guide on how to answer a summons for debt collection covers the response that prevents this stage entirely, and a debt collection lawsuit hearing works differently from the narrow motion described here.
Where judgment has already been entered by default, our walkthrough of a default judgment for debt covers how that happens and what it authorizes.
5. Ask the Court to Stop Collection, Because Your Motion Will Not Do It
This is the most consequential fact in this article and the one readers are told least often. Under the federal rule, a motion for relief from a judgment does not affect the judgment’s finality and does not suspend its operation.
Read that as an operational fact rather than a technicality. A garnishment taking money from your paycheck keeps taking it while your motion sits on the docket. A levy already placed on your account stays placed. Anyone who files to challenge an incorrect judgment and then waits will keep losing money for the entire time they believe the problem is being handled.
Stopping collection is a request separate from the motion to challenge an incorrect judgment, made to the same court, asking that enforcement be paused while the motion is decided. It is a distinct thing to ask for and it is not granted automatically because you asked for relief from the judgment.
Ask for both at once. When you file, ask the clerk what request pauses enforcement while a motion is pending, and file it alongside. Readers moving to challenge an incorrect judgment while wages are being taken should treat the pause request as the urgent half of the filing, because it is the half that affects this month.
Separately, the protections attaching to specific income and specific accounts continue to apply regardless of any motion to challenge an incorrect judgment and operate independently of it. If wages are the target, our guide to stopping a wage garnishment covers those mechanisms, and the Federal Trade Commission’s debt collection answers set out which federal benefits creditors cannot reach at all.
6. Prepare for the Hearing and Know What Winning Actually Gets You
Many motions to challenge an incorrect judgment may be decided on written submissions, sometimes with a hearing, but state and local courts may use different procedures, so preparation means being able to state the error in under a minute and hand up the document that proves it.
Readers preparing to challenge an incorrect judgment should bring three things. The judgment as entered. The record that contradicts it. A one-page timeline of what happened and when. Everything else is commentary, and commentary makes short hearings long without making them better.
Say the error, not the history. Judges hearing these motions decide a narrow question, and the answer they need is what specifically is wrong with this judgment and what proves it. A reader who arrives to explain how unfairly the whole debt was handled has answered a question nobody asked.
Then understand what the two ways to challenge an incorrect judgment produce, because the outcomes differ enormously. A correction changes the number or the name and leaves everything else standing. Rowena’s judgment becomes a judgment for $4,930 and remains a judgment, enforceable, on her record, collecting interest. Fixing the amount was worth doing and did not make the debt disappear.
Setting a judgment aside is different in kind. It removes the judgment and returns the case to where it stood beforehand, which usually means the lawsuit is live again and a response is due. That is the better outcome and it is not the end of the matter, and a reader who wins on a void-service ground and then ignores the revived case ends up exactly where they started. If the judgment turns out to be valid after all, our guide on how to negotiate debt after judgment covers what leverage remains.
Money already collected is its own question, decided by the court on the record and the ground for relief, and it is not automatic. Anyone who succeeds should ask specifically about funds already taken.
Mistakes That Sink Otherwise Winnable Challenges
The errors below sink otherwise winnable attempts to challenge an incorrect judgment and have nothing to do with the merits. Each is a way to lose while being right, which makes them worth more attention than the law itself.
Writing to the collector instead of filing with the court. A letter to the law firm is not a motion. No clock stops, nothing goes on the record, and the reader believes the problem is being handled.
Assuming one year applies to everything. It applies to three grounds. Readers with void or satisfied judgments talk themselves out of a route that is still open, which is the most expensive mistake made by people trying to challenge an incorrect judgment.
Filing and then waiting. Enforcement continues. Without a separate request to pause it, the garnishment runs for the life of the motion.
Arguing the whole debt at a narrow hearing. The motion is about a defect in the judgment, and a hearing spent on the fairness of the underlying debt spends its time on the wrong question.
Treating a correction as a discharge. Fixing the amount fixes the amount. The judgment survives, and readers who stop paying attention after a partial win are surprised twice.
Ignoring the revived lawsuit after a win. Setting the judgment aside restores the case, and a default entered a second time is a genuinely avoidable outcome.
Frequently Asked Questions
Can I challenge an incorrect judgment if it was entered more than a year ago? Sometimes, and the answer depends entirely on what is wrong with it. Under the federal model, clerical errors may be corrected whenever they are found, with no time limit, and grounds such as a void judgment or one already satisfied or discharged carry no one-year cap either. The one-year limit applies to mistake or excusable neglect, newly discovered evidence, and fraud. Your state sets its own periods, so ask the clerk of the court that entered the judgment.
Does filing a motion stop a garnishment that is already taking money? No, and this is the most costly misunderstanding in the subject. The federal rule states that the motion does not suspend the judgment’s operation. Pausing enforcement is a separate request to the same court and it is not automatic.
What if I was never served with the lawsuit at all? That is the strongest ground most readers have to challenge an incorrect judgment. A judgment entered without proper service is the standard example of a void judgment, and under the federal model a void judgment is not subject to the one-year limit.
Do I need a lawyer to challenge an incorrect judgment? Not necessarily, and it depends on the ground. A clerical correction supported by documents is the most self-serviceable request in this area. Setting a judgment aside on a substantive ground involves a real legal standard, and a legal aid organization in the county where the judgment was entered is worth contacting before deciding to proceed alone.
What happens to money already taken if I win? It is not returned automatically. Whether funds already collected come back is decided by the court based on the record and the ground on which relief was granted, and it is a question to raise specifically rather than assume.
Will a motion to challenge an incorrect judgment hurt my credit further? Filing is a court procedure, not a credit event in itself. Civil judgments generally are not included in modern nationwide consumer credit reports. The underlying account or public court record may have separate effects, and a court motion does not itself guarantee a particular bureau result.
What Rowena Learned
The motion to challenge an incorrect judgment worked, and the transposition was corrected. It took one filing, one exhibit, and one short appearance before a judge who spent less than four minutes on it, and the judgment against her now reads $4,930.
What she says about the experience is not about the money. It is that she spent nearly a year believing she had missed her chance, because everything she read described a one-year deadline that did not apply to her situation at all. The route she needed had never closed. Nobody had told her there was more than one route.
That is the practical lesson worth carrying out of this. Learning how to challenge an incorrect judgment is mostly learning which kind of wrong you are dealing with, because the answer determines the clock, the filing, and whether you still hold a right you were told you had lost.
Here Are More Articles That Might Interest You
Readers who need to challenge an incorrect judgment also need to know what enforcement looks like while the motion is pending, and these guides cover the stages around it.
If wages are being taken right now, our walkthrough of how to claim a garnishment exemption explains the protection a paycheck never receives automatically.
Readers whose account has been hit should read how to claim a bank levy exemption, which covers recovering money already seized.
If an account froze this week, our guide on what to do when a bank account is frozen after a judgment covers the first days.
Anyone ordered to appear and answer questions should read what a judgment debtor examination involves before the date arrives.
If written demands arrived in the mail, our guide to a post judgment discovery request explains the deadline nobody sees.
Readers with a shared account should read whether a collector can take money from a joint account.
Anyone worried a spouse will be pulled in should read whether a collector can garnish a spouse’s wages.
Readers with nothing collectible should understand what it means to be judgment proof.
And if a levy has already reached an account, our answer to whether collectors can take money from your bank account covers how that works.
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.