The knock came at 6:40 on a Tuesday evening. David was clearing the dinner dishes when he opened the door to a stranger holding a folded stack of papers. “You’ve been served,” the man said, and walked back to his car. David stood in the doorway reading the words Summons and Complaint over and over, his stomach in knots.
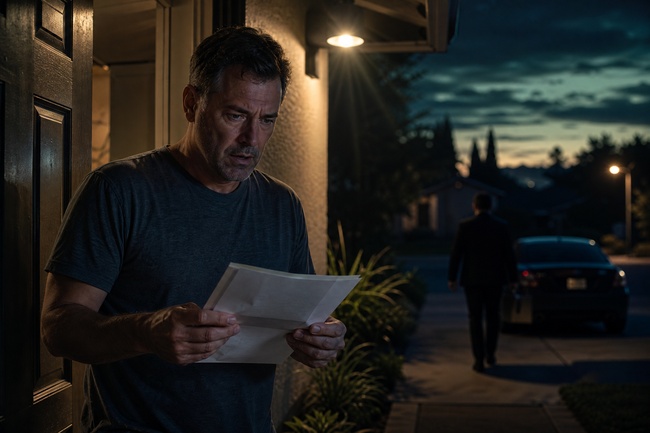
A debt collector he’d never heard of was suing him for a credit card he’d stopped paying two years earlier — and the papers said he had just 20 days to respond. He didn’t have money for a lawyer. What he needed to know, right then, was how to answer a summons for debt collection on his own — and whether doing it himself could actually work.
Here’s the truth that debt collectors hope you never learn: it can. And in most cases, it’s far easier than you think.
At The Debt Survival Guide, our team draws on over 45 years of CPA experience helping people untangle exactly these kinds of financial emergencies. We’ve seen what happens when people ignore a lawsuit — and what happens when they fight back. This guide walks you through how to answer a summons for debt collection step by step, without hiring a lawyer, so you can protect your paycheck, your bank account, and your peace of mind.
Table of Contents
What a Debt Collection Summons Actually Means
To know how to answer a summons for debt collection, start with the official notice, and learning how to answer a summons for debt collection starts by explaining that someone has filed a lawsuit against you. It arrives with a second document called a complaint (in some states, a petition), which lists the plaintiff’s claims against you in numbered paragraphs — who is suing you, how much they say you owe, and why they believe a court should make you pay.
When learning how to answer a summons for debt collection, getting served feels terrifying. Knowing how to answer a summons for debt collection can make the next step more manageable. But a summons is not a judgment. It is not a garnishment order. Nobody is taking your money yet. A summons simply means the collector has started a legal process — and you now have a limited window to participate in it.
For anyone learning how to answer a summons for debt collection, that window matters more than anything else in learning how to answer a summons for debt collection. Debt-collection lawsuits are a major category of civil cases, and a cited Pew analysis reported that, in the jurisdictions and period studied, according to The Pew Charitable Trusts, more than 70% ended in default judgment in that study — a serious risk when a defendant does not respond. Fewer than one in ten defendants has a lawyer, so treat answering as a practical deadline task and follow the controlling court rules.
If you are learning how to answer a summons for debt collection, read that again. That is why answering before the deadline matters. Collectors don’t win most of these cases because their evidence is strong. They win because nobody shows up.
If your summons involves a credit card account, and you need to know how to answer a summons for debt collection, specifically, compare the account records with our companion guide on what to do when you’re sued for credit card debt covers the full defense strategy from service to trial. This article focuses on the single most important document in that fight: your Answer.
Why You Must Respond: The Default Judgment Trap
When you do not respond by the deadline, the plaintiff may ask the court for a default judgment. The court may grant it without a trial when procedural requirements are met and the defendant does not respond; the exact process depends on current court rules. The plaintiff may obtain amounts proven or allowed under applicable law, plus interest, court costs, and often attorney fees stacked on top.
If you are learning how to answer a summons for debt collection and the deadline passes with no answer on file, the collector wins automatically — a devastating outcome we break down fully in our guide to what a default judgment for debt is and how to fix it.
A default judgment can transform a collection claim from a demand into an enforceable court order, which is why you should not wait. Depending on your state, a judgment holder can garnish your wages, place liens on your property, and freeze the funds in your bank account, as the Consumer Financial Protection Bureau warns. We cover exactly how account freezes work — and which funds are protected — in our guide on whether debt collectors can take money from your bank account.
Here is what makes the trap so serious when someone does not respond: many people who get default judgments entered against them had winnable cases. The debt was past the statute of limitations. The collector couldn’t prove it owned the account. The amount was inflated. Those defenses may be limited after default depending on court rules and the facts.
When you learn how to answer a summons for debt collection, filing an Answer changes everything. It is the practical core of how to answer a summons for debt collection. The moment you respond, a response may require the plaintiff to support its claims, subject to pleading and evidence rules — original account records, a documented chain of ownership, an accurate accounting of the balance. Some debt-buyer cases may weaken when challenged if the plaintiff cannot produce adequate account documentation. Some cases may be dismissed, but dismissal is not guaranteed. If a later judgment threatens your account, review whether debt collectors can take money from your bank account before assuming every dollar is reachable.
Responding does not mean admitting that you owe the debt. It preserves your opportunity to contest the claim rather than allowing a default process to continue.
How to Answer a Summons for Debt Collection in 7 Steps
Learning how to answer a summons for debt collection comes down to one document — the Answer — and a handful of procedural rules. Follow these seven steps carefully and you’ll have a properly filed response that forces the collector to prove every claim.
Step 1: Read the Summons and Complaint Carefully
Before you write a single word while learning how to answer a summons for debt collection while deciding how to answer a summons for debt collection, extract these facts from your court papers:
- Your deadline. This is printed on the summons itself. The deadline printed on the summons and applicable current court rules control; examples vary by court and jurisdiction. Never assume; read your summons.
- The court. Note the exact court name, county, and case number. Everything you file must match this information precisely.
- The plaintiff. Is it your original creditor, or a debt buyer with an unfamiliar name like “Midland Credit” or “Portfolio Recovery”? This distinction shapes your defense.
- The amount claimed. Compare it against your own records. Inflated balances are common.
When learning how to answer a summons for debt collection, mark your deadline on a calendar while organizing how to answer a summons for debt collection in red. Every step that follows must be finished before that date.
Step 2: Verify the Debt and Who Is Suing You
As you learn how to answer a summons for debt collection, remember that debts get sold and resold, and paperwork gets lost along the way. Before you concede anything, make the plaintiff show its work. If a collection agency contacted you before filing suit, you had the right to demand verification — our free debt validation letter template shows exactly how that process works and why it matters.
Once a lawsuit is filed, learning how to answer a summons for debt collection requires understanding that the same principle applies inside the courtroom: a plaintiff must prove it has standing, meaning it actually owns your debt and has the legal right to sue you for it. Debt buyers must produce a documented chain of title tracing your account from the original creditor to their portfolio. It’s one of the most commonly missing pieces of evidence in collection cases — and one of the most powerful defenses available to you.
While learning how to answer a summons for debt collection, pull together everything you have: old statements, payment records, settlement letters, and correspondence. You’re building the file you’ll rely on for the rest of the case.
Step 3: Respond to Every Numbered Allegation
When learning how to answer a summons for debt collection, remember that the complaint states its claims, and your Answer should respond to each numbered allegation in order. Your Answer responds to each one, using one of three responses:
- Admit — the statement is true. Only admit facts you know are correct, such as your name and address.
- Deny — the statement is false or you dispute it.
- Deny for lack of knowledge (or “insufficient information to admit or deny”) — you genuinely can’t confirm it. Courts treat this as a denial.
Here is the golden rule for anyone learning how to answer a summons for debt collection when drafting an Answer: when unsure, respond truthfully, avoid unsupported admissions, and seek legal help. Anything you admit, the collector no longer has to prove. A denial may require the plaintiff to support its claim, subject to pleading and evidence rules. Many pro se defendants make the fatal mistake of admitting the entire debt in their Answer out of a sense of honesty — before ever seeing whether the plaintiff can prove ownership, the balance, or the terms of the original agreement.
A typical paragraph in your Answer may read:
“Defendant denies the allegations contained in Paragraph 4 of Plaintiff’s Complaint for lack of sufficient information to admit or deny the same.”
For people learning how to answer a summons for debt collection, some states use standardized fill-in-the-blank Answer forms to simplify how to answer a summons for debt collection (California’s PLD-C-010 and Texas’s justice court Answer form are good examples), which make this even simpler. Check your court’s website or ask the clerk whether a form exists for your court.
Step 4: Raise Your Affirmative Defenses
An affirmative defense is a legal reason the plaintiff may not prevail, even if the debt was once real. Here’s the critical rule: courts may require affirmative defenses in an Answer, depending on jurisdiction and rules; the effect of omission also depends on those rules. The applicable pleading rules and deadlines require careful attention. We’ll cover the strongest defenses in detail in the next section, but the most common include an expired statute of limitations, lack of standing, improper service, and payment already made.
When you learn how to answer a summons for debt collection, a defense should be stated consistently with applicable pleading and sanction rules; identify defenses that plausibly fit your situation and seek legal help when unsure.
Step 5: Format Your Answer Correctly
If your court does not provide a fill-in form, you will draft the Answer yourself using the court’s required format. The format is simpler than most people expect:
- The caption. Copy the header from the complaint exactly — court name, county and state, plaintiff’s name, your name, and the case number.
- The title. Center the word “ANSWER” (or “Defendant’s Answer to Plaintiff’s Complaint”) below the caption.
- Your responses. Numbered paragraphs admitting, denying, or denying for lack of knowledge, matching the complaint paragraph by paragraph.
- Affirmative defenses. A separate section listing each defense.
- Your request. A short closing sentence asking the court to dismiss the complaint and grant any other relief it deems just.
- Signature block. Your signature, printed name, address, phone number, and email. Unrepresented defendants sign as “Defendant, Pro Se.”
- Certificate of service. A short sworn statement saying when and how you sent a copy to the plaintiff’s attorney.
When learning how to answer a summons for debt collection, keep the tone factual and unemotional while preparing your Answer. The Answer is not the place to explain a job loss or medical crisis — save your story for settlement talks or trial. The Answer’s only job is to deny what should be denied and preserve your defenses.
Step 6: File Your Answer With the Court Clerk
This is the step that makes your response official. Take your signed Answer — plus at least two copies — to the clerk of the court named on your summons, or use the court’s e-filing system if it has one. The clerk stamps your original and copies with the filing date. Keep a stamped copy in a safe place permanently; it’s your proof that you responded on time.
When learning how to answer a summons for debt collection, some courts charge a filing fee for an Answer, typically ranging from nothing (Texas justice courts are free) to several hundred dollars (California’s answer fee runs $225 to $450). If you can’t afford the fee, ask the clerk for a fee waiver application — some courts offer fee-waiver procedures, subject to court-specific eligibility and approval.
Step 7: Serve the Plaintiff and Keep Proof of Everything
When learning how to answer a summons for debt collection, filing with the court is only half the job. You must also deliver (“serve”) a copy of your Answer to the plaintiff’s attorney — or the plaintiff directly if no attorney is listed — usually by mail. Use the service method and timing required or accepted by the court; certified mail, return receipts, and same-day service are not universal requirements.
As part of learning how to answer a summons for debt collection, set up a simple case file: your stamped Answer, the summons and complaint, the certified mail receipt, and every document related to the debt. From this point forward, anything the court or the plaintiff mails you goes in the file, and every deadline goes on your calendar. Missed mail can damage a case as seriously as a bad argument. That organized file is part of how to answer a summons for debt collection effectively.
Affirmative Defenses That Can Win Your Case
Preserving each plausible defense is an important part of answering a collection lawsuit. The table below summarizes the defenses that appear most often in consumer debt cases and when each one applies.
| Affirmative Defense | What It Means | When It Applies |
|---|---|---|
| Statute of limitations | The plaintiff waited too long to sue | The debt is older than your state’s limit (often 3–6 years) |
| Lack of standing | The plaintiff can’t prove it owns the debt | The plaintiff is a debt buyer, not your original creditor |
| Improper service | You weren’t legally served with the lawsuit | Papers were left with the wrong person or never delivered |
| Payment or settlement | The debt was already paid or settled | You have receipts, statements, or a settlement letter |
| Incorrect amount | The balance claimed is inflated | Fees, interest, or charges don’t match your records |
| Mistaken identity / identity theft | The debt isn’t yours | Fraud, mixed files, or a name mix-up |
| Discharged in bankruptcy | The debt was wiped out by a bankruptcy court | You received a discharge that covered this account |
When learning how to answer a summons for debt collection, the statute of limitations deserves special attention because it’s both powerful and perishable. Limitations periods vary by state and debt type, and tolling or revival rules may apply; do not rely on a single range. Courts may not apply it automatically. If you do not raise it in your Answer, you may lose the defense under applicable rules. Check your state’s deadline in our complete guide to the statute of limitations on debt by state before you file.
If you are learning how to answer a summons for debt collection, one warning about making a payment — even a small “good faith” one — may affect limitations under state-specific tolling or revival rules. Never agree to a payment on an old debt until you’ve checked whether it’s already time-barred.
Deadlines by State: How Long Do You Have?
When learning how to answer a summons for debt collection, response deadlines vary by state and by court type, and the deadline printed on your summons always controls. The ranges below show how much variation exists — and why you should never rely on a friend’s experience in another state. Follow the summons itself and the current court rules.
| Deadline Window | Example States / Courts |
|---|---|
| 14 days | Texas (justice court) |
| 20–21 days | Florida, Virginia (varies by court), Louisiana |
| 28–30 days | California, Illinois, South Carolina, Ohio, and most other states |
| 30+ days | Some states when served by mail or publication |
When learning how to answer a summons for debt collection, three general rules are useful, but court rules control. First, the clock usually starts the day you’re served, not the day the suit was filed. Second, weekends and holidays may or may not count, depending on your court’s rules — when in doubt, file early. Third, if your deadline has already passed, don’t give up: until the court actually enters a default judgment, most courts will still accept your Answer. Call the clerk, confirm whether a default has been entered, and file immediately if it hasn’t.
What Happens After You File Your Answer
Filing your Answer changes the case after you prepare it correctly. You’re no longer a name on a default list — you’re a party the plaintiff must actually litigate against. Here’s what typically comes next. This is a practical next step.
The collector re-evaluates after you learn how to answer a summons for debt collection. This is one possible result after you learn how to answer a summons for debt collection. Collection law firms run high-volume operations built on defaults. A filed Answer with real defenses instantly makes your case more expensive to pursue. A significant share of cases are voluntarily dismissed after a defendant responds, especially when a debt buyer can’t locate account-level proof.
Discovery may begin after you learn how to answer a summons for debt collection. Either side can request documents and written answers from the other. Use this to your advantage: ask the plaintiff to produce the original signed agreement, a complete payment history, and the full chain of title. If they can’t, say so in a motion or at trial.
Settlement talks often open. They may follow a filed Answer, but they are not guaranteed. Once a collector realizes you won’t default, a negotiated resolution frequently becomes their preferred exit. You have real leverage at this stage — often enough to settle for a fraction of the claimed balance. Our step-by-step guide on how to negotiate a debt settlement shows how to run that negotiation and get every term in writing before you pay a dime.
A hearing or trial may be scheduled as the court process advances. If the case proceeds, show up — prepared, on time, with your file. Some pro se defendants prevail when the plaintiff.s representative fails to appear or cannot produce admissible evidence.
If you learn how to answer a summons for debt collection and the debt is legitimate and the total picture of what you owe feels unmanageable even with a good defense, step back and look at the bigger strategy. Our comparison of bankruptcy versus debt settlement walks through when each path makes sense — sometimes a lawsuit is the push that leads to a genuinely fresh start.
Mistakes to Avoid When Answering a Debt Collection Summons
After watching thousands of these cases play out, the practical lessons are consistent: the same errors appear again and again. Avoid these and you’re ahead of the vast majority of defendants.
Calling the collector instead of following the court process can undermine your case. This is one of the most dangerous mistakes. Phone calls don’t stop the lawsuit clock, and anything you say — including an innocent “yes, that was my card” — can be used against you. Worse, a partial payment made over the phone can revive a time-barred debt. If collector calls are wearing you down during the case, you have a legal right to limit them; see our guide on how to stop debt collectors from calling.
When learning how to answer a summons for debt collection, do not admit everything in the Answer. Honesty is a virtue; volunteering legal admissions is not. Deny what you can’t verify and make the plaintiff prove its case.
Missing the deadline while “getting ready.” People researching the process sometimes get stuck polishing their defenses while the clock runs out. A simple, timely Answer beats a perfect, late one. File something adequate before the deadline; you may be able to amend it if the court rules and deadline permit.
Ignoring mail after filing can undo careful work on your case. Discovery requests, hearing notices, and motions all arrive by mail, and each carries its own deadline. Unanswered discovery can sink an otherwise strong case.
When learning how to answer a summons for debt collection, do not pay a “debt relief” company to handle the lawsuit. Many settlement mills take large fees and never file anything with the court. If an offer of easy forgiveness sounds too good to be true, read our breakdown of whether credit card debt forgiveness is real or a scam before signing anything.
Assuming you can’t get help. Many people can prepare an Answer without a lawyer, but the process and available help vary, but free help exists if your case gets complicated. Legal help may be available through LSC-funded organizations, subject to eligibility, capacity, and local coverage — search the Legal Services Corporation directory to find free legal help near you. Understanding how to answer a summons for debt collection yourself doesn’t mean you have to do everything alone.
Frequently Asked Questions
What is the first step in how to answer a summons for debt collection?
The first step in learning how to answer a summons for debt collection is reading the summons and complaint carefully to identify your deadline, the court, the plaintiff, and the amount claimed. Your response deadline — the deadline printed on the summons and applicable current court rules — controls everything else, so mark it immediately and work backward from there.
Can I really answer a debt collection summons without a lawyer?
Yes. When learning how to answer a summons for debt collection, remember that courts allow you to represent yourself (“pro se”), and many states provide fill-in-the-blank Answer forms designed for people without attorneys. Fewer than one in ten defendants in debt collection lawsuits has a lawyer, yet defendants who file may improve their opportunity to contest claims or negotiate, but dismissal or settlement is not routine or guaranteed. If your case becomes complex, free legal aid may be available in your area. Before paying for a debt-relief service, compare its promises with whether credit card debt forgiveness is real or a scam.
What happens if I ignore a summons for debt collection?
When learning how to answer a summons for debt collection, ignoring a summons can increase the risk of a default judgment — an automatic court win for the collector that adds interest, court costs, and attorney fees to the balance. With a judgment, the collector may be able to garnish your wages, freeze your bank account, or place a lien on your property, depending on your state. More than 70% was reported in the cited Pew research for the jurisdictions and period studied; it is not a universal current national rate, but responding still matters.
How much does it cost to answer a summons for debt collection?
When learning how to answer a summons for debt collection, it depends on the court. Verify the filing fee with the clerk before filing. Some courts, including Texas justice courts, may charge no filing fee, while other courts set fees under their own schedules. Fee waivers may be available under court-specific eligibility rules — ask the court clerk for the fee waiver application when you file.
What is the best defense against a debt collection lawsuit?
When learning how to answer a summons for debt collection, the strongest defenses are usually an expired statute of limitations (the collector sued after your state’s legal deadline) and lack of standing (a debt buyer can’t document that it owns your debt). Both may need to be raised in your written Answer, or you may risk waiving them under applicable rules. Improper service, prior payment, and incorrect balance calculations are also common winning defenses.
Can I still settle the debt after filing my Answer?
When learning how to answer a summons for debt collection, absolutely — and filing may improve your procedural position, but it does not guarantee stronger leverage or settlement. Once the collector knows a default judgment is off the table, a settlement for less than the full balance may be possible, but it is not guaranteed. Get any settlement agreement in writing, signed by the plaintiff, and confirm the written agreement and dismissal terms under the court’s procedure before paying.
Take Back Control of Your Financial Future
Being served with a lawsuit can feel like the bottom, but learning the process can be the moment you begin taking back control. One document, filed on time, changes you from a statistic into a fighter with real leverage. And once the lawsuit is behind you, momentum matters: our guide comparing the debt snowball versus debt avalanche methods shows how to turn that leverage into a payoff plan that ends the debt cycle for good.
Sources & References
- Consumer Financial Protection Bureau: Debt collection guidance
- The Pew Charitable Trusts: Debt collection court research
- Legal Services Corporation: Find legal help
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.