Yolanda had done everything right for nineteen months. Rebuild savings while paying debt requires a plan for the next emergency, not just discipline for the last one. She cut cable, packed lunches, took a weekend shift at a garden center, and threw every spare dollar at her credit cards. A $14,200 balance fell to $3,900. Then her transmission died on a Wednesday in a grocery store parking lot, and the repair came to $2,840. She had eleven dollars saved, so it went on the card she had nearly cleared.
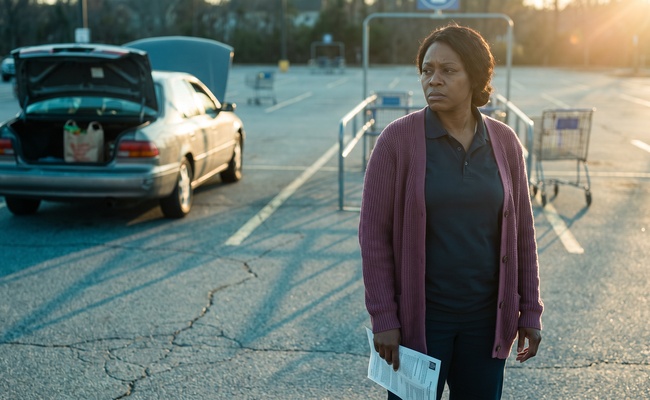
Within a week she was back above $6,700. Nineteen months of discipline undone by one Wednesday. Yolanda had not failed at paying debt. She failed to build the one thing that protects payoff from ordinary life, which is why people must rebuild savings while paying debt rather than sequence them.
Learning to rebuild savings while paying debt is not a compromise or weak commitment. It is the difference between progress that holds and progress that gets erased. The Consumer Financial Protection Bureau states the risk plainly in its essential guide to building an emergency fund: without savings, even a minor financial shock can set you back, and if it becomes debt, the impact lasts.
This guide covers six steps to rebuild savings while paying debt without stalling payoff, plus where to keep the money and what counts as an emergency.
At The Debt Survival Guide, our team draws on over 45 years of CPA experience to help people evaluate difficult financial decisions with clarity and caution. We understand that the decision to rebuild savings while paying debt feels like choosing between two responsibilities, because every dollar saved looks like a dollar that could have gone to a balance. This guide explains why a household with no cushion keeps restarting its payoff, how to size a first cushion, where to keep the money, and how to define an emergency. Because interest rates and individual circumstances vary widely, educational information cannot replace individualized financial advice.
Table of Contents
Why Paying Debt With Zero Cushion Keeps Failing
The math of aggressive payoff is compelling. Every dollar sent to a high-interest balance earns a guaranteed return equal to that rate, which is why advice says to attack debt with everything. The logic is sound in a vacuum, and nobody lives in one, which is the case for choosing to rebuild savings while paying debt.
Cars break. Teeth crack. Water heaters fail. Hours get cut. With no cash reserve, each event has one funding source: credit. The balance you spent months reducing climbs back in an afternoon, often at a higher rate.
The CFPB describes the pattern directly: people who struggle to recover from a shock have less savings for the next one. They rely on cards or loans, creating debt that is harder to pay off, and sometimes raid retirement funds. Missing savings is not separate from debt. It regenerates debt, which is why you rebuild savings while paying debt rather than after.
A second cost gets underestimated. As the CFPB notes, a one-time emergency expense may grow far larger than the original bill through interest and fees. Yolanda’s $2,840 transmission could cost more if carried at 24 percent; the final cost and added months depend on the payment schedule, compounding, and fees.
So the choice to rebuild savings while paying debt is not between two goals. It is between payoff that survives reality and payoff that resets whenever something breaks.
What the Federal Guidance Actually Says About How Much
Before you set a target to rebuild savings while paying debt, know something that contradicts much popular advice. The CFPB publishes no fixed dollar figure and no number of months. Its guidance states the amount depends on your situation, and recommends a different starting point: the unexpected expenses you have actually had, and what they cost.
That is more useful and more achievable. If your last three surprises were a $400 dental bill, a $600 brake job, and a $250 vet visit, your real exposure is near $600, not six months of rent. A buffer matching your pattern helps immediately, while someone else’s formula feels so distant you never start.
The CFPB is direct about paycheck-to-paycheck reality, acknowledging that saving feels difficult on irregular or fully committed income, then making the point that matters: even a small amount provides some financial security. You do not have to solve the whole problem to get real protection from it.
As you rebuild savings while paying debt, a practical first milestone covers your single most likely emergency. Once it exists, the next can be larger. The first buffer is not about comfort. It breaks the automatic link between a bad Wednesday and a higher card balance.
Step One: Build a Starter Buffer Before You Accelerate Payoff
Sequencing stops people, so here it is plainly. Keep every required minimum payment. Then, before directing extra money at accelerated payoff, send it to a starter buffer until that buffer covers your most likely emergency. That order is the core of how you rebuild savings while paying debt.
This is not a permanent reordering of priorities but a temporary detour, usually weeks to a few months, that protects everything after it. An extra payment reduces your balance; a buffer prevents it from growing. When you rebuild savings while paying debt, prevention is worth more because your exposure is total.
Consider Yolanda’s arithmetic as illustration, not promise. Ten weeks of setting aside $280 a month would have given her about $700 when the transmission failed. Not the whole repair, but a quarter less on the card and months off the recovery.
Once the starter buffer is funded, flip the flow. Every extra dollar returns to debt and the buffer sits untouched until something breaks. You did not lose payoff speed permanently when you chose to rebuild savings while paying debt. You bought insurance against losing it entirely.
Step Two: Find the Money in Timing Rather Than New Income
Most advice assumes you have not tried. Readers already paying debt aggressively have cut what can be cut. The opportunity to rebuild savings while paying debt is rarely in spending less. It is in timing.
The CFPB calls this managing cash flow: the timing of money coming in against money going out. When that timing is misaligned, you run short at the end of a week even though monthly totals work. Tracking it reveals gaps you can use to rebuild savings while paying debt.
The move the CFPB recommends is one many never try. You may be able to work with the parties you owe, including your landlord, utilities, and card companies, to adjust due dates. Moving two bills from the first to the sixteenth can convert a chronic shortfall into a small surplus without changing a spending decision.
The second half uses weeks when more money is available. Paid biweekly, two months a year contain a third paycheck. The CFPB’s guidance is to move extra into savings during those windows rather than absorbing the surplus into ordinary spending.
If your budget needs rebuilding first, our guide to creating a realistic debt repayment budget walks through the structure. The FTC makes the same point in its guidance on how to get out of debt: a budget shows where money goes and how to redirect it.
Step Three: Automate the Transfer So Willpower Is Not the Mechanism
Every month you decide whether to save is a month you might not. The CFPB identifies automatic saving as among the easiest ways to keep contributions consistent, and consistency is what makes a buffer appear when you rebuild savings while paying debt.
The standard version is a recurring transfer from checking to savings, scheduled through your bank or credit union on a day and amount you choose. Set it the day after payday, so the money leaves before it can be spent on something reasonable.
The CFPB attaches a warning that matters most for readers carrying debt. Watch your balances so an automatic transfer does not trigger an overdraft fee. One fee can exceed a month of saving, turning a good habit into a net loss.
Two protections handle this. Start smaller than you think you can afford, because a transfer that never fails beats one that overdrafts. And use the balance notifications the CFPB recommends, so you see a shortfall coming.
A second route bypasses checking entirely. The CFPB notes many employers can split a direct deposit between two accounts, sending part of your pay straight to rebuild savings while paying debt from your checking account. Ask payroll whether a split deposit is available.
Step Four: Use One-Time Money to Jump the Buffer Forward
Monthly increments are slow, which is why the fastest way to rebuild savings while paying debt usually runs through money that arrives all at once.
The CFPB identifies the tax refund as the clearest opportunity, calling it one of the largest checks many Americans receive all year. Its guidance is direct: while it is tempting to spend, saving all or a portion could quickly establish your fund and rebuild savings while paying debt.
Note the phrase “all or a portion.” The CFPB is not asking for austerity, and neither am I. A refund that funds your entire starter buffer in one deposit has done something no monthly transfer can do in the same timeframe, and keeping a modest slice for something enjoyable makes the decision sustainable rather than punishing.
This step matters most with irregular income, and the CFPB says so, identifying one-time opportunities as particularly helpful when pay fluctuates. If you cannot commit to a fixed monthly transfer, lump-sum saving may be your main way to rebuild savings while paying debt rather than a supplement.
One caution. If you are weighing sending a refund to a balance instead, you can do both: as you rebuild savings while paying debt, the buffer comes first only until it covers your likely emergency. After that, refunds are excellent debt payments. Our guide to which debts to pay first helps you decide where a lump sum does the most good once the buffer exists.
Step Five: Protect the Buffer From Collection Pressure
This step is absent from general savings advice, because that advice does not assume a collector has your number. When you rebuild savings while paying debt behind on accounts, the balance creates a vulnerability worth understanding early.
Collectors ask what you have available, sometimes in ways that make withholding feel dishonest. You are not required to inventory your accounts, and disclosing a balance often converts a flexible negotiation into a demand for exactly that amount. Our guide to debt negotiation scripts covers language for staying cooperative without volunteering financial detail.
Know the rules governing contact. The FTC’s debt collection FAQs explain what collectors can and cannot do, including contact limits and disputes in writing. Those boundaries make it easier to hold your position while you rebuild savings while paying debt.
One structure targets savings capacity directly. The FTC describes how for-profit debt settlement programs require monthly set-asides until you can pay a lump sum, while often urging you to stop paying creditors. Your capacity to rebuild savings while paying debt becomes their fee engine as accounts go delinquent. Our comparison of credit counseling versus debt settlement lays out the tradeoffs.
The FTC also flags the record-keeping habit that protects you. Keep records of who you talked to and what you agreed to, and make sure any agreement arrives in writing.
Step Six: Keep Paying Debt While the Buffer Grows
The failure mode here is not overspending. It is drifting into savings-only mode, because watching a balance grow feels better than watching one shrink. To rebuild savings while paying debt, both must continue.
Minimums stay non-negotiable while you rebuild savings while paying debt. The FTC states the stakes: miss minimums for several months and a creditor may eventually charge off the debt, depending on the account type and creditor policy; you may still owe it and your credit may be affected. That account can then be sold to a collector.
If the minimums are out of reach, do not abandon the plan. The FTC’s guidance is to call creditors before a collector is involved, explain the situation, and propose a manageable payment plan. For cards it recommends asking for a lower rate, and adds a point worth repeating: you do not need to pay a company to make that call.
A written request documents a temporary situation better than a call, and our guide to writing a hardship letter to creditors covers what to include and ask for.
Once the buffer is funded, return to full attack mode. Order matters less than people think, but it matters, and our comparison of the debt snowball versus debt avalanche methods explains the tradeoff between speed and momentum as you rebuild savings while paying debt.
Where to Keep the Money So You Do Not Spend It
Location matters more than it sounds, because when you rebuild savings while paying debt the money must be safe, reachable in a real emergency, and slightly inconvenient otherwise.
The CFPB lists three options. A bank or credit union account is generally among the safest places for your money, making a dedicated savings account the default. A prepaid card, which spends only what is loaded, is a workable alternative. Cash is third, with the CFPB’s warning that it can be stolen, lost, or destroyed.
For most readers, a separate savings account at the same institution as checking is the practical choice. It transfers instantly in a real emergency, and the extra step is just enough friction to interrupt an impulse.
One thing to avoid: do not treat available room on a credit card as your safety net. Available credit is not savings. It is future debt at a variable price, and the issuer can reduce the room without your consent.
Deciding What Actually Counts as an Emergency
A buffer spent on non-emergencies is not a buffer, and one you refuse to spend on real emergencies is not useful either. Both failures come from never defining the word.
The CFPB advises setting your own guidelines for what counts as an emergency, acknowledging not every unexpected expense is dire, and staying consistent. The rule matters less than applying it the same way in March as in November.
A workable test has three parts. The expense is genuinely unplanned. It affects your ability to work, stay housed, stay healthy, or stay safe. And delaying it makes it worse. A failed transmission on your work car passes all three. A sale passes none.
The CFPB is clear that medical costs count even when undramatic, noting you may need the fund for a bill insurance did not cover. If a medical bill emptied your buffer as you rebuild savings while paying debt, our guide to negotiating medical bills with hospitals can often reduce the amount before you pay it.
What to Do After You Have to Spend It
The most important sentence in the CFPB’s emergency fund guidance is the one people skip: do not be afraid to use it if you need it. If you spend down your emergency savings, build it up again, and practicing over time makes it easier.
Spending the buffer is not failure. It is the buffer working as designed. The failure is the alternative: putting the emergency on a card and adding to the balance you are trying to eliminate.
The recovery sequence is the one you already ran, and it is faster because the habit exists. Pause extra debt payments. Restart the transfer. Rebuild to your milestone. Return to accelerated payoff. That loop is how you rebuild savings while paying debt over the long run.
What changes is your relationship to the bad Wednesday. Yolanda’s transmission cost nineteen months of progress because she had eleven dollars. Against a funded buffer, the same repair costs a frustrating weekend and about ten weeks of rebuilding. That is the entire value of learning to rebuild savings while paying debt.
The CFPB frames consistent saving as a habit: set a goal, build a system, monitor progress, and recognize each milestone. That last part sounds soft, but efforts to rebuild savings while paying debt are long and undramatic, and unmarked progress feels like deprivation. Our debt payoff calculator guide models how much faster payoff moves once emergencies stop resetting it.
Your First Two Weeks: A Practical Plan
Use this sequence to rebuild savings while paying debt without stalling anything.
Day one: write down your last three unexpected expenses and what each cost. The largest is your starter buffer target.
Day two: confirm every minimum payment and due date. These continue uninterrupted while you rebuild savings while paying debt. If any is beyond reach, call that creditor this week.
Day three: open a separate savings account at the institution holding your checking, so transfers are immediate.
Day four: map thirty days of cash flow timing and identify the week you run short.
Day five: ask one or two of the parties you owe to move a due date into the week where you have room. Landlords, utilities, and card issuers often accommodate this.
Day six: set an automatic transfer for the day after payday, small enough that it never overdrafts. Turn on balance notifications at the same time.
Day seven: ask payroll whether your direct deposit can be split between two accounts so you can rebuild savings while paying debt.
Week two: write your own one-sentence definition of an emergency and post it where you will see it. Then send any one-time money, including a tax refund, to the buffer until your target is funded.
Frequently Asked Questions
Should I really pause extra debt payments to save, when the interest keeps accruing?
For the short period it takes to fund a starter buffer, yes. When you rebuild savings while paying debt, minimums continue, so nothing goes delinquent. Interest accrued during a brief pause is almost always less than the interest from charging a full emergency to a card and carrying it for months.
How much should my emergency fund hold?
The CFPB publishes no fixed figure and states the amount depends on your situation. Its method is to look at the unexpected expenses you have actually had. As you rebuild savings while paying debt, a first milestone covering your single most likely emergency beats a large number that feels unreachable.
What if my income is different every month?
Lean on one-time money rather than fixed transfers to rebuild savings while paying debt. The CFPB identifies lump-sum saving, including tax refunds, as particularly helpful with irregular income. Save more in strong weeks and do not treat a missed transfer as failure.
Can a collector take money from my savings account?
Not simply because you have it. A collector generally needs a court judgment before attempting to reach bank funds, and certain protected income stays off limits even then. Rules vary by state. What you control now is not volunteering the balance during a negotiation.
Is it better to keep the buffer in a high-yield account?
Yield is the least important factor. Safety, accessibility, and separation from spending matter more. The CFPB names a bank or credit union account as generally among the safest. Interest on a modest buffer is a rounding error next to avoiding one emergency charged at card rates.
What if an emergency hits before the buffer is funded?
Use what you have accumulated, cover the rest however you must, then restart your effort to rebuild savings while paying debt. Partial coverage still reduces what goes on credit, and the second build is faster.
Should I use a credit card as my emergency fund instead?
No. Available credit is not savings when you rebuild savings while paying debt. It is future debt at a variable price, and the issuer can cut your limit without warning. The CFPB notes a one-time expense can grow well beyond the original bill once interest and fees accumulate.
Here Are More Articles That Might Interest You
Decide whether you should use your emergency fund to pay off debt before you drain the cushion you just started building.
See how much interest the credit card minimum payment trap actually costs, which is what makes the savings question feel impossible.
Learn how to negotiate a lower credit card interest rate, the fastest way to free up room for both goals at once.
Check whether a high debt to income ratio is the real constraint on how much you can set aside each month.
Compare the full range of debt relief options if the payments themselves are the reason nothing can be saved.
Ask about credit card hardship programs when a temporary income drop is what emptied the account.
Weigh the pros and cons of debt consolidation before combining balances in the hope of finding margin.
Understand the difference between secured and unsecured debt so you know which balances to protect first when cash is short.
Watch for debt relief scam warning signs, since promises of instant savings target people in exactly this position.
Learn how credit utilization affects your score so paying down balances also repairs your credit file.
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.