When Marcus checked his credit score after paying off his car loan, he expected it to go up. Instead, it dropped 23 points.
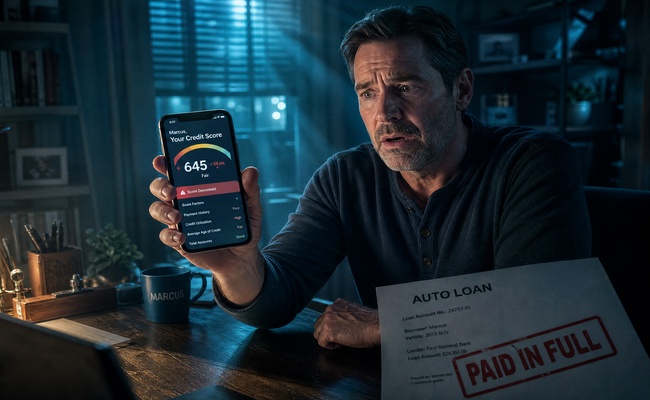
His credit card balances had not changed, his payment history was perfect, and he had not opened any new accounts. The surprise led him to a factor many people overlook: the balance reported on a revolving account can affect utilization.
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Short answer: Credit utilization is the portion of your available revolving credit that is being used. Keeping balances low can help, but no percentage guarantees a score, approval, or rate because scoring models consider the full credit profile.
Table of Contents
What Is Credit Utilization?
Credit scoring models look at utilization in two ways: per-card utilization and overall utilization across all your revolving accounts. Both matter for utilization and your score. If you have three cards with limits of $5,000, $8,000, and $12,000 and balances of $4,000, $2,000, and $1,000, your overall utilization is $7,000 divided by $25,000, which equals 28%. However, that first card has 80% utilization individually, which can still hurt your score even though your overall number looks reasonable.
Only revolving credit accounts like credit cards and lines of credit factor into utilization calculations. Installment loans like mortgages, car loans, and student loans have their own separate scoring factors and do not count toward your utilization ratio. This distinction matters because many people confuse total debt with utilization and your score suffers when revolving balances are high regardless of how much installment debt you carry. You could owe $200,000 on a mortgage and still have excellent utilization if your credit card balances are low relative to their limits.
This is why someone with massive student loan debt can still have an 800 credit score as long as their credit card utilization remains in single digits. The key takeaway is that utilization is based on revolving balances relative to their limits. Paying down revolving balances may help, but it is only one part of a credit profile.
The Scoring Thresholds That Matter
Credit scoring models may not treat utilization as a simple linear scale, but the relevant thresholds for utilization and your score and their effects vary by scoring model and consumer profile. Staying below commonly discussed ranges may help, but no single threshold guarantees a particular score.
The 30% figure is a commonly cited guideline, not a universal scoring cutoff. Some research and scoring profiles associate very low utilization, sometimes in the 1% to 9% range, with higher scores, but the effect on utilization and your score varies by model and profile. You do not need to carry a balance to build utilization and your score.
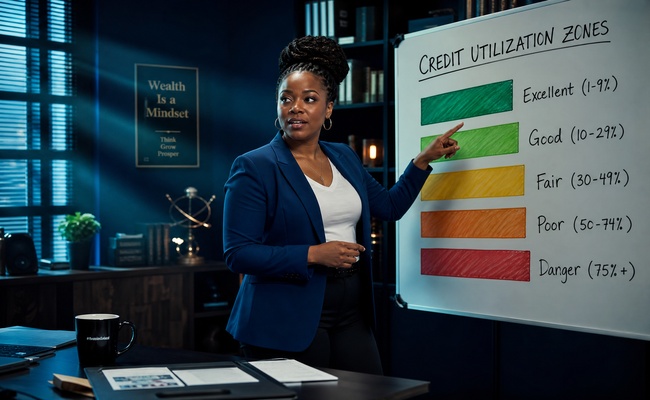
Ranges such as 10% to 29%, 30% to 49%, 50% and above, and 75% and above are useful educational reference points for utilization and your score, not universal score thresholds. The effect can vary by scoring model, lender, credit profile, and the information reported for the account, so a change from one range to another does not guarantee a particular score increase or decrease.
Checking your reported balances monthly can help you understand patterns before you apply for credit. These ranges are educational reference points, not promises about a particular score change. you crossed a key threshold in the utilization and your score calculation.
Why Utilization Changes Every Month
Unlike payment history, which builds gradually over years, utilization and your score can shift dramatically from one month to the next. This volatility happens because most credit card issuers report your balance to the credit bureaus once per month, typically on your statement closing date rather than your payment due date. This means your reported balance reflects whatever you owed on that specific day, not your average usage throughout the month.
This reporting timing creates a situation where you could pay your card in full every month and still show high utilization if your statement closes before your payment posts. For example, if you charge $4,000 on a card with a $5,000 limit during the month and your statement closes on the 15th, the bureau sees 80% utilization even though you pay the full balance on the 20th.
Understanding this timing relationship between utilization and your score gives you the ability to strategically manage what gets reported. Most people have no idea that the date their statement closes determines what the credit bureaus see, which means they are leaving score points on the table every single month without realizing it.
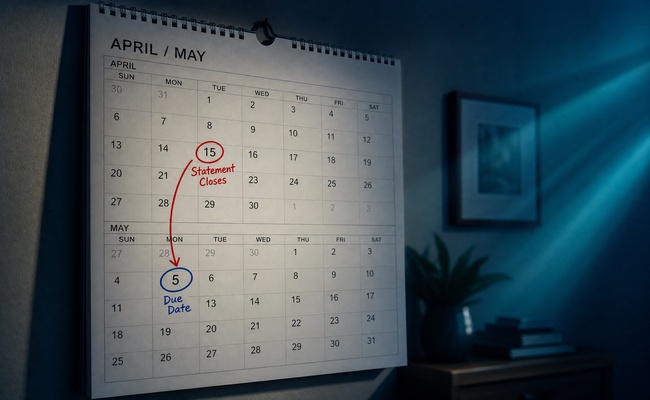
Once you understand when your issuer reports account information, you can ask whether paying earlier may reduce the balance that is reported. The result depends on the issuer, reporting cycle, and timing of the payment. A lower reported balance may help, but the size and timing of any score change vary by scoring model and credit profile.
The good news about utilization volatility is that it has no memory. Unlike a late payment that damages your credit for seven years, high utilization only hurts your score for the month it is reported. A lower balance may help after it is reported, but the timing and size of any change vary.
Because reported balances can change from cycle to cycle, utilization may be more responsive than some other score factors. Do not treat a lower balance as a guaranteed or immediate score result.
Strategic Timing: When to Pay Your Balance
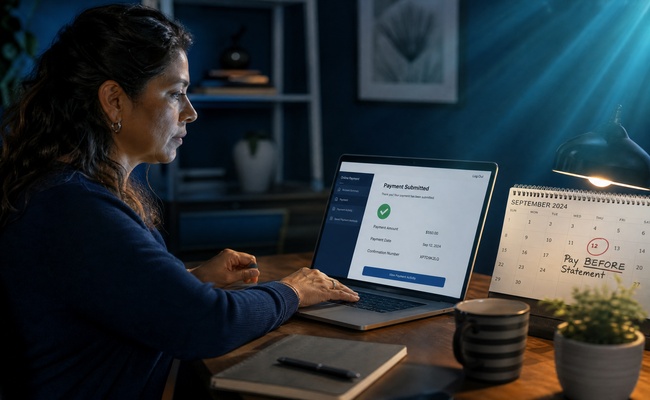
The most powerful technique for managing utilization and your score is paying down your balance before your statement closing date rather than waiting for the due date. Most people pay their credit card bill when it is due, which may be several weeks after the statement closes, depending on the account terms. By that time, the higher balance has already been reported to the bureaus.
To optimize utilization and your score, make a payment a few days before your statement closing date to reduce the balance that gets reported. You do not need to pay the full amount early. Even a partial payment that lowers the reported balance may help, although no percentage guarantees a score result. Call your card issuer or check your online account to find your exact statement closing date, then set a calendar reminder to make a payment two to three days before that date each month.
This strategy is particularly valuable when you are preparing to apply for credit. In the one to two months before a mortgage application, car loan, or apartment rental, paying your cards down to below 10% utilization before the statement closes may improve your score, although the amount varies by model and profile. Any effect may appear after the lower balance is reported, but the timing and amount vary. If you are working to escape the credit card minimum payment trap, reducing utilization is an added benefit of paying more than the minimum each month.
While paying down balances is ideal, reducing your interest rate means more of each payment goes toward the balance itself. Our guide on how to negotiate a lower credit card interest rate shows you how a single phone call can accelerate your utilization improvement by directing more money toward principal reduction.
A balance transfer card serves double duty for your utilization ratio. Our guide on balance transfer strategies explains how transferring a balance to a new card simultaneously increases your total credit limit and eliminates interest charges, creating a potentially useful combination for improving your utilization ratio.
Want to see exactly how quickly extra payments will reduce your utilization ratio? Our guide on how to use a debt payoff calculator lets you model different payment amounts and see how your balances and utilization percentage drop month by month.
The Credit Limit Connection
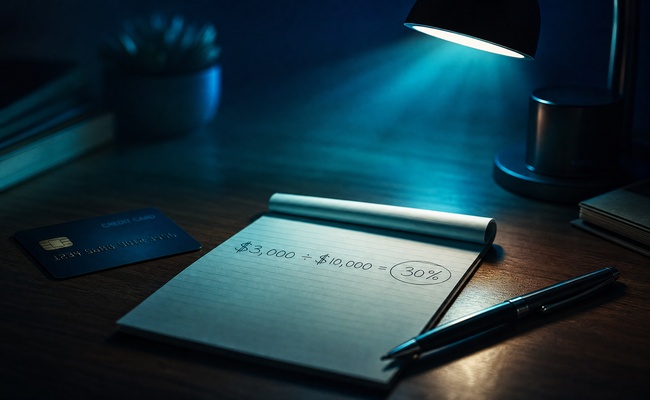
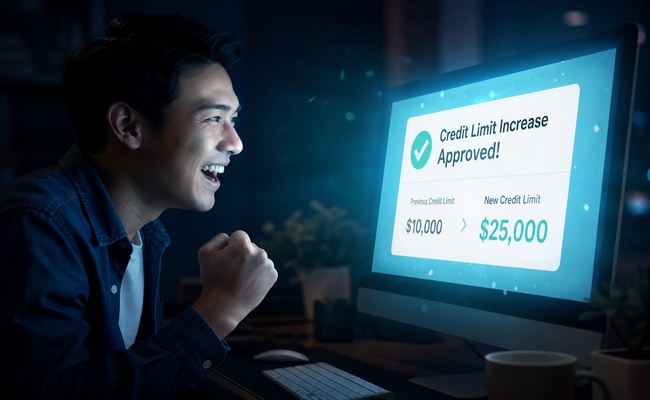
There are two ways to reduce your utilization ratio: lower your balances or increase your credit limits. Both achieve the same mathematical result for utilization and your score. If you have a $3,000 balance on a $10,000 limit, your utilization is 30%. You can reduce it to 15% either by paying the balance down to $1,500 or by getting your limit increased to $20,000 while keeping the same balance.
Requesting a credit limit increase is often the easier path when paying down balances is not immediately feasible. Some issuers may review a limit-increase request with a hard inquiry and others may not. Ask the issuer how the request will be handled before submitting it. The Federal Trade Commission notes that managing your available credit responsibly is a key component of overall financial health. A higher limit with the same spending habits automatically improves utilization and your score without requiring any change in your payment behavior. Many people successfully improve their scores by 20 to 40 points simply by requesting limit increases on their existing cards without spending a single additional dollar.
If you have been a responsible cardholder for more than a year, learning to negotiate with your card issuer can also result in better terms alongside a higher limit. Combining a rate reduction with a limit increase creates a double benefit for utilization and your score because you pay less interest while simultaneously improving your ratio.
However, a limit increase only helps if you do not use it as permission to spend more. If your limit goes from $10,000 to $15,000 and you immediately charge an additional $5,000, your utilization stays the same and you now have more debt. The discipline to maintain the same spending level after a limit increase is what makes this strategy effective for improving utilization and your score over time.
Multiple Cards: Spreading Your Balances
Because scoring models evaluate both individual card utilization and overall utilization, strategically spreading your spending across multiple cards can improve utilization and your score even without reducing your total debt. A single card at 60% utilization hurts more than three cards each at 20% utilization, even though the total dollar amount of debt is the same.
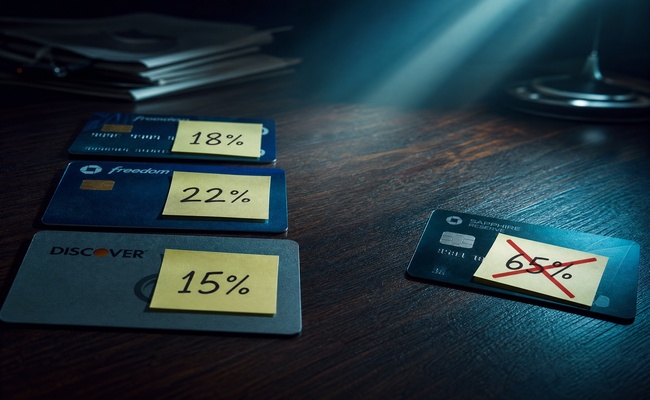
This does not mean you should open new cards solely to reduce utilization, as new accounts temporarily lower your average account age. But if you already have multiple cards, distributing your regular spending across them rather than concentrating it on one card keeps individual utilization low. Spreading balances may reduce the percentage used on an individual card, but scoring models and profiles differ, so it is not a guaranteed penalty or score outcome. Think of it as spreading risk across your credit profile rather than concentrating it in one vulnerable spot. This distribution strategy is one of the simplest ways to improve utilization and your score without making any additional payments beyond what you already spend each month.
If you are considering consolidating multiple card balances into one account, be aware that this can temporarily increase utilization on the receiving card even though it simplifies your payments. Our guide on debt consolidation pros and cons explains how to weigh the convenience of one payment against the potential utilization impact on utilization and your score.
Common Mistakes That Spike Utilization
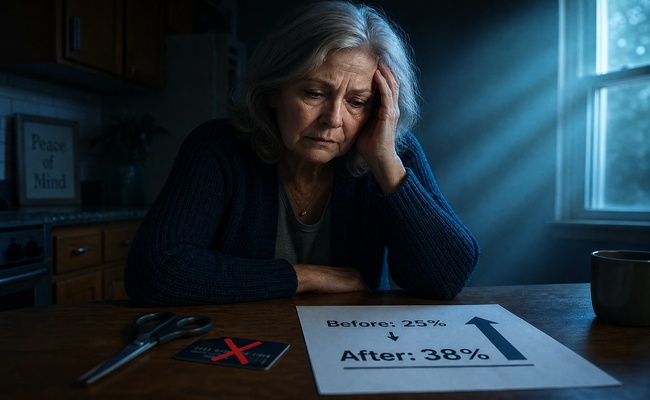
Several common financial moves can unexpectedly spike your utilization and damage utilization and your score. Closing a credit card can increase utilization because it may reduce your total available credit while your remaining balances stay the same. Whether closing is right depends on fees, terms, debt, and the rest of your credit profile. If you have $5,000 in total balances across three cards with $20,000 in total limits, your utilization is 25%. Close one card with a $7,000 limit, and your utilization jumps to 38% overnight without spending a single additional dollar.
This mathematical reality is why Some consumers keep older accounts open because their limits and payment history may help, but the CFPB says the effect of closing an account varies and closing can sometimes be reasonable. The only exception is if a card carries an annual fee that you cannot justify, in which case ask the issuer to downgrade it to a no-fee version rather than closing the account entirely. This preserves the credit limit in your total available credit calculation while eliminating the ongoing cost. Always explore the downgrade option before closing any card, as the impact on utilization and your score from a closure can take months to recover from.
The best practice is to keep old cards open even if you rarely use them, make a small purchase on inactive cards every few months to prevent the issuer from closing them, and monitor your utilization ratio monthly. Building awareness of how utilization and your score interact on a daily basis transforms credit management from a mystery into a controllable process that you can optimize month after month. If you are working on a realistic debt repayment budget, tracking utilization alongside your payoff progress shows you exactly how each payment improves both your debt level and your credit score simultaneously.
Frequently Asked Questions
Does checking my own credit utilization hurt my score?
No. Checking your own credit report or score is a soft inquiry that has zero impact on utilization and your score. You can check as often as you want through your card issuer’s free score tool, Credit Karma, or AnnualCreditReport.com without any negative effect. Monitoring regularly is actually recommended so you can catch unexpected utilization spikes before they cause problems. Staying aware of utilization and your score on a weekly basis takes less than two minutes and can prevent costly surprises.
Should I pay my credit card to zero every month?
You do not need to carry a balance to build a good score. Paying in full can reduce interest costs; a small reported balance may affect different scoring models differently, so there is no need to pay interest just to create a balance.
Does my utilization ratio affect my ability to get new credit?
Yes, utilization can affect how lenders evaluate an application, but lenders use different scoring models and consider more than one factor. Higher utilization may be viewed less favorably, but no percentage guarantees approval or a particular rate. Keep balances as low as practical before applying without taking on unaffordable payments.
Here Are More Articles That Might Interest You
Learn about credit counseling vs debt settlement as options for managing high balances that are keeping your utilization elevated.
If you are overwhelmed by multiple high-balance cards, our guide on what to do first when drowning in debt provides a starting framework.
Our guide on how long debt consolidation takes helps you plan if combining balances is your strategy for reducing utilization.
Find out about debt management plan pros and cons as a structured approach to paying down balances and improving utilization over time.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Credit scores, reporting practices, and account terms vary by person and issuer. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.