Natalie stared at the stack of envelopes on her kitchen counter and felt her chest tighten. Three credit cards maxed out, a medical bill from last winter she had never opened, and now a letter threatening legal action over an old personal loan. She was 42, worked full-time as a pharmacy technician, and could not figure out how she had ended up here. She was drowning in debt, and every morning felt like waking up underwater with no idea which direction led to the surface. If you recognize that feeling — the paralysis, the shame, the sense that nothing could possibly matter against such an enormous weight — this guide is for you.
At The Debt Survival Guide, our team draws on over this guide provides general educational information helping individuals navigate financial crises that feel impossible to solve. The strategies in this article are not theoretical — they reflect real-world triage methods used by financial professionals when clients arrive drowning in debt with no clear starting point. The recommendations below are educational starting points; check them against current federal and state rules and your specific facts before acting.
Table of Contents
Why Drowning in Debt Feels Like Actual Paralysis
When you are drowning in debt, the psychological weight often does more immediate damage than the financial numbers themselves. Research in behavioral economics shows that financial overwhelm triggers the same stress hormones as physical threats — cortisol floods your system, your prefrontal cortex shuts down higher-order planning, and you default to avoidance. That avoidance accelerates the very consequences you fear most.
The critical insight is this: the feeling of being overwhelmed is not a character flaw. It is a predictable neurological response to having too many competing demands with unclear priorities. The solution is not willpower. The solution is a triage system that removes the need to decide everything at once and replaces chaos with a single next step.
People who are drowning in debt often describe the same pattern: they know they need to do something, but every option feels equally urgent and equally impossible. Should they answer the collector calling three times a day? Should they pay the minimum on the credit card or put that money toward rent? Should they file bankruptcy? The sheer volume of decisions creates a gridlock where nothing gets done at all.
Step 1 — Stop Everything and Breathe (Seriously)
Before you open a single envelope or make a single phone call, you need to do one thing: accept that you will not solve this today. That is not defeat — that is strategy. People drowning in debt make their worst decisions in the first 48 hours of panic. They sign up for predatory consolidation loans. They drain retirement accounts and trigger tax penalties. They agree to payment plans they cannot sustain. Read our complete analysis of whether using your 401k to pay off debt is ever worth the devastating tax penalties and lost compound growth.
Pause new financial commitments long enough to complete the triage steps below, while still opening notices, protecting essential accounts, and following any court, housing, utility, insurance, or benefits deadline. Do not ignore urgent notices or deadlines while gathering information.
Step 2 — Secure the Four Walls First
This is the most important concept for anyone drowning in debt: your survival needs come before your creditors. Period. The “four walls” framework means you allocate your available income in this exact priority order before a single dollar goes to unsecured debt.
Wall 1: Food. You and your family eat first. This means groceries — not restaurants, not convenience stores — but actual food in your home. If money is so tight that food is at risk, contact your local 211 helpline or visit your state’s SNAP benefits portal immediately.
Wall 2: Shelter. Your rent or mortgage payment keeps a roof over your head. If you are behind, contact your landlord or mortgage servicer directly. Most have hardship options they will not advertise unless you ask. Eviction and foreclosure timelines vary by state, court, servicer, landlord, and individual facts; contact the relevant party promptly and follow the written notices and deadlines.
Wall 3: Basic utilities. Electricity, water, heat. Most utility companies offer payment plans and hardship programs. Many states prohibit utility shutoffs during extreme weather. Call before you miss a payment, not after.
Wall 4: Transportation to work. If you need a car to earn income, the car payment and minimum insurance come next. If you rely on public transit, that monthly pass is a wall-four expense. Without transportation, you lose income, and the entire situation collapses.
Everything else — credit cards, medical bills, personal loans, collections — comes after these four walls are secured. This is important to evaluate, subject to essential needs, deadlines, and individual circumstances. This is how professionals triage when someone is drowning in debt with limited resources.
Step 3 — Write Down Every Debt You Owe
Once your four walls are covered for this month, your next step is a complete debt inventory. Get a piece of paper or open a spreadsheet and list every single debt. For each one, write down the creditor name, total balance owed, minimum monthly payment, interest rate, and whether the account is current, past due, or in collections.
This step terrifies people who are drowning in debt because they have been avoiding the total number. But here is what happens when you write it all down: the number is finite. It has edges. It is no longer an amorphous monster lurking in the dark — it is a specific figure that can be addressed with specific strategies.
Do not skip debts because they feel too small or too old to matter. Pull your free credit reports from all three bureaus and cross-reference them against your own records. You may find debts you forgot about, and you may also find errors that can be disputed and removed.
Step 4 — Separate Secured Debt From Unsecured Debt
Now divide your inventory into two columns. Secured debts are attached to collateral — your mortgage is secured by your home, your auto loan is secured by your car. If you stop paying, the creditor can take the asset. Unsecured debts have no collateral — credit cards, medical bills, personal loans, and most collection accounts fall here.
This distinction matters enormously when you are drowning in debt because it determines the actual consequences of nonpayment. A missed mortgage payment can lead to foreclosure. A missed credit card payment leads to late fees, interest, and eventually collections — but nobody takes your house over a credit card. Understanding this hierarchy prevents the catastrophic mistake of paying unsecured creditors at the expense of your four walls.
Secured debts that protect essential assets always get priority. Unsecured debts get addressed with whatever remains after your four walls and secured obligations are covered.
For older collection accounts, review the statute of limitations in your state before deciding how urgently to respond.
Step 5 — Identify Which Debts Are Actually Dangerous Right Now
Not all debts carry the same urgency. When you are drowning in debt, you need to identify which accounts pose an immediate legal or financial threat versus which ones are simply generating angry letters. Here is how to assess each debt on your list.
High danger: Any debt with an active lawsuit filed against you. If you have been served with a summons, your response deadline is the date printed on the summons and the applicable court rules. Missing that deadline can result in a default judgment that may allow collection remedies such as wage garnishment or a bank levy after required procedures, subject to exemptions and state law.
Medium danger: Debts that are severely past due (90+ days) with original creditors who have not yet charged off the account. These creditors still have the option to sue, and the account is actively deteriorating on your credit report.
Lower danger: Debts already in collections, especially older ones approaching the statute of limitations in your state. Old debts can still carry legal risk; collection agencies may sue, and the applicable rules vary by state and facts.
This assessment tells you where to focus your limited energy and money. The debt screaming loudest — the collector calling five times a day — is not necessarily the most dangerous. The quiet lawsuit sitting in your mailbox is.
Step 6 — Stop the Bleeding on High-Danger Debts
If you have an active lawsuit or a debt about to trigger wage garnishment, that is your immediate priority. Respond to any court summons within the deadline — even if your response is simply denying the claims and requesting that the creditor prove the debt. Filing a timely answer may help avoid a default judgment and preserve time to explore options, but it does not guarantee the result.
If garnishment is already in progress, you may be able to file a claim of exemption to protect a portion of your income. Federal law protects the greater of 75 percent of your disposable earnings or 30 times the federal minimum wage per week. Your state may offer even stronger protections. Learn more about how to stop wage garnishment with specific legal steps.
For debts in collections that are not yet at the lawsuit stage, you have the right to request written verification within 30 days of the date on a validation notice. For a covered debt collector, the FDCPA validation process gives you a defined period to dispute information in the validation notice and request supporting information; the exact notice and dispute rules matter.
Step 7 — Create a Bare-Bones Survival Budget
With your four walls secured and your high-danger debts identified, you need to know exactly how much money you have available each month for everything else. This is not a normal budget. This is a crisis budget — stripped down to absolute necessities only.
List your total monthly take-home income. Subtract your four walls expenses. Subtract any minimum payments on secured debts you are keeping. The number that remains is your “debt-fighting fund” — the amount available to address unsecured debts, build a tiny emergency buffer, or fund a settlement offer.
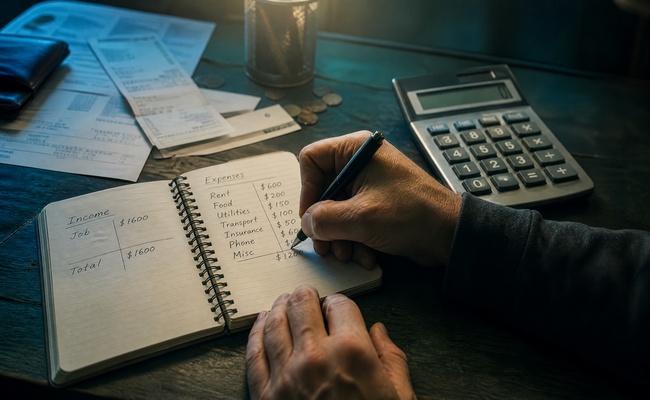
If you need a more detailed framework for building this crisis budget, our guide on creating a realistic debt repayment budget walks you through every category step by step and shows you how to find hidden money you did not know you had.
If that number is zero or negative, you are not failing at budgeting — you have an income-to-expense crisis that no payment strategy can solve. Your next steps involve increasing income (overtime, gig work, selling unused items) or reducing expenses further (negotiating bills, eliminating subscriptions, seeking assistance programs). People drowning in debt often discover that their problem is not poor money management — it is simply that their income cannot cover their obligations, and that requires structural solutions rather than willpower.
Step 8 — Choose a Debt Attack Strategy
Once you have stabilized your four walls, addressed any legal emergencies, and identified your available monthly surplus, you can choose how to tackle the remaining unsecured debt. The two most common approaches are the debt snowball and debt avalanche methods.
The snowball method pays off the smallest balance first regardless of interest rate, giving you quick psychological wins. The avalanche method targets the highest interest rate first, saving more money over time. Both work. The best method is the one you will actually stick with when you are exhausted and tempted to give up.
For people drowning in debt with very large balances, a third option exists: negotiating settlements for less than the full amount owed. Some creditors or collectors may consider negotiated settlements, but no creditor is required to accept a particular amount and outcomes vary. Settlement can affect credit, taxes, costs, and legal rights, so compare the terms with other options.
Step 9 — Protect Yourself From Collector Harassment
When you are drowning in debt, collection calls become a daily source of anxiety that makes clear thinking nearly impossible. You need to know that federal law gives you significant power over how and when collectors can contact you. The Consumer Financial Protection Bureau enforces these protections.
Collectors cannot call before 8 a.m. or after 9 p.m. They cannot use abusive language or threaten actions they have no legal authority to take. They cannot discuss your debt with your family or employer beyond a single attempt to locate you. If a collector violates these rules, they may owe you damages under the FDCPA.
You also have the right to send a written cease-and-desist letter requesting that a collector stop contacting you, subject to permitted limited follow-up contact under the FDCPA. This does not erase the debt, but it generally stops further communications except limited follow-up permitted by law and gives you space to think strategically rather than reactively. Many people drowning in debt find that silencing the constant collector contact is the single most important step for regaining mental clarity.
Step 10 — Know When to Ask for Professional Help
There is no shame in recognizing that your situation requires professional guidance. If you are facing active lawsuits, your total unsecured debt exceeds your annual income, or you are considering bankruptcy, consulting with a professional can prevent costly mistakes.
Nonprofit credit counseling agencies offer some free initial consultations and can help you evaluate whether a debt management plan makes sense for your situation. Bankruptcy attorneys offer free initial consultations in some cases as well.
Be cautious of any company that charges large upfront fees, guarantees specific results, or pressures you to stop paying creditors without explaining the legal consequences. Legitimate professionals explain risks honestly and never guarantee outcomes they cannot control.
What NOT to Do When You Are Drowning in Debt
Knowing what to avoid is just as important as knowing what to do. When panic sets in, people drowning in debt frequently make decisions that worsen their situation. Avoid these traps.
Do not drain your retirement accounts. Some ERISA-qualified plans and some IRAs receive protection, but coverage differs by plan, account type, bankruptcy exemptions, state law, and the collection context. Withdrawing them to pay unsecured debt eliminates that protection, triggers income taxes on the withdrawal, adds a 10 percent early withdrawal penalty if you are under 59½, and leaves you with nothing for the future.
Do not take out a consolidation loan without doing the math. Consolidation can help if it genuinely lowers your interest rate and you can afford the new payment. But many people drowning in debt use consolidation to lower monthly payments by extending the term — which means paying far more in total interest over time. Worse, if the consolidation loan is secured by your home, you have converted unsecured debt into a foreclosure risk.
If you are considering consolidation despite being drowning in debt, make sure you understand all the risks first. Our complete guide to debt consolidation pros and cons explains when it helps, when it hurts, and the specific warning signs that a consolidation loan will make your situation worse.
Do not ignore court documents. If you are served with a lawsuit, responding is important to evaluate, subject to essential needs, deadlines, and individual circumstances. Even if you owe the money, filing an answer preserves your rights, forces the creditor to prove their case, and opens the door to negotiating a settlement from a position of legal engagement rather than default.
Do not pay a debt that is past the statute of limitations without understanding the consequences. Making a payment on time-barred debt can restart the legal clock in some states, giving the creditor a fresh window to sue you. Verify the statute of limitations in your state before sending any money to old debts.
The Emotional Reality of Drowning in Debt
Financial crisis is not just a numbers problem. People drowning in debt report higher rates of anxiety, depression, insomnia, and relationship conflict. The shame associated with debt makes people isolate themselves precisely when they need support most. If you are experiencing thoughts of self-harm related to financial stress, the 988 Suicide and Crisis Lifeline is available 24 hours a day.
The emotional recovery often lags behind the financial recovery. Even after the numbers start moving in the right direction, the anxiety may persist for months. That is normal. It does not mean your plan is failing. It means your nervous system needs time to recalibrate after an extended period of threat.
Give yourself credit for reading this far. The fact that you searched for help and are building a plan rather than hiding — that is the hardest step. Everything after this is mechanics.
Frequently Asked Questions
What is the first thing I should do if I am drowning in debt?
The first thing to do when drowning in debt is secure your four walls — food, shelter, utilities, and transportation to work. These survival needs take absolute priority over any unsecured creditor. Once your basic needs are covered, create a complete debt inventory and identify which debts pose immediate legal threats. This triage order prevents panic-driven mistakes that make the crisis worse.
Can I lose my house if I am drowning in debt from credit cards?
Credit card debt alone cannot directly cause you to lose your home because it is unsecured — there is no collateral attached. However, if a credit card company sues you, wins a judgment, and places a lien on your property, it could complicate a future sale. The greater risk is paying credit card bills at the expense of your mortgage, which can lead to foreclosure. Always prioritize your mortgage over unsecured debt when drowning in debt.
Should I file for bankruptcy if I am drowning in debt?
Bankruptcy is a legitimate legal tool — not a moral failure — but it should be considered after evaluating all alternatives. If your total unsecured debt exceeds what you could reasonably repay within five years using your disposable income, or if you are facing lawsuits you cannot defend, bankruptcy may provide the fastest path to a fresh start. Consult with a bankruptcy attorney for a free evaluation of your specific situation. The FTC’s guide to getting out of debt outlines the major options available.
How do I stop debt collectors from calling when I am drowning in debt?
You have the legal right to send a written cease-and-desist letter to any debt collector requesting that they stop further contact, subject to permitted limited follow-up under the FDCPA. Under the FDCPA, covered collectors generally must comply after receiving your letter, subject to limited follow-up permitted by law. This does not eliminate the debt, but it generally stops further communications except limited follow-up permitted by law and gives you mental space to plan strategically. You can also request that collectors communicate only in writing, which creates a paper trail and eliminates the pressure of live phone conversations.
Is debt consolidation a good idea when drowning in debt?
Debt consolidation can help if it genuinely reduces your interest rate and you can afford the new single payment without extending the term excessively. However, consolidation is not debt reduction — you still owe the same total amount. It becomes dangerous when people consolidate and then continue accumulating new debt on freed-up credit cards, or when the consolidation loan is secured by their home, converting unsecured risk into foreclosure risk.
How much debt is too much debt?
Debt-to-income ratios can be useful context, but lender definitions and limits vary and current consumer guidance commonly uses gross income rather than take-home pay. Treat any percentage as an illustration, not a universal danger zone. The real answer is personal: if your debt causes you to miss basic needs, lose sleep, or avoid your mail, the amount is too much regardless of what any ratio says.
Here Are More Articles That Might Interest You
If you are drowning in debt and a collector is already calling, learn exactly how to stop debt collectors from calling using federal law.
When drowning in debt leads to a lawsuit, knowing how to answer a summons for debt collection can prevent a default judgment.
People drowning in debt often wonder whether credit card debt forgiveness is real or a scam — here is the truth.
If drowning in debt has you considering settlement, find out whether debt settlement hurts your credit and how long the damage lasts.
Collectors may threaten to take your money directly — learn whether debt collectors can take money from your bank account and how to protect yourself.
When drowning in debt feels criminal, understand the real answer to whether you can go to jail for debt in the United States.
If you stopped paying and are drowning in debt from credit cards, learn exactly what happens if you stop paying credit cards month by month.
People drowning in debt with old accounts should understand zombie debt and why collectors pursue debts you thought were gone.
If you are drowning in debt and creditors are threatening your paycheck, here is what happens if you ignore a debt collector completely.
When drowning in debt pushes you toward asking your bank for help, explore credit card hardship programs that most banks offer but rarely advertise.
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.