Talia watched the balance in her checking account fall before her paycheck had even cleared. Two weeks earlier, a payday lender had given her $400 to cover an urgent repair. The fee looked manageable when she signed the agreement, but the repayment date arrived before her rent, utilities, and groceries were covered. Rolling the loan forward seemed like the only way to keep the account from overdrafting. It was also the moment she realized she was entering a payday loan debt trap.
That trap is not caused by a lack of effort. It happens when a short repayment period collides with an income schedule that cannot absorb the full balance and fee. The next renewal may solve one immediate problem while preserving the original principal, and each new fee can make the following payday even tighter. Understanding the mechanics early can help you compare safer alternatives before the loan consumes money needed for essential bills.
At The Debt Survival Guide, our team draws on over 45 years of CPA experience to help people evaluate difficult financial decisions with clarity and caution. A payday loan debt trap can involve high costs, repeated renewals, electronic withdrawals, and collection pressure, but the safest response is not always the most dramatic one. The goal is to protect essential living expenses, understand the written agreement, stop the cycle from deepening, and choose a realistic next step based on your income and obligations.
Table of Contents
What Is a Payday Loan Debt Trap?
A payday loan debt trap often begins with a small, short-term loan designed to be repaid from a future paycheck. The lender may receive a personal check or permission to debit your bank account for the borrowed amount plus fees. Because the full balance can be due within a few weeks, the loan may be difficult to repay if the borrower’s next paycheck is already committed to housing, food, transportation, utilities, insurance, or other debt payments.
The payday loan debt trap begins when the borrower can pay the fee but not the original principal. That is the point when a payday loan debt trap deserves a written exit plan rather than another rushed renewal. A lender may offer a rollover or renewal that extends the due date in exchange for another fee. The original balance remains, while the borrower has less money available during the next pay period. Repeating that decision can turn a short-term cash advance into an ongoing obligation that competes with every other bill.
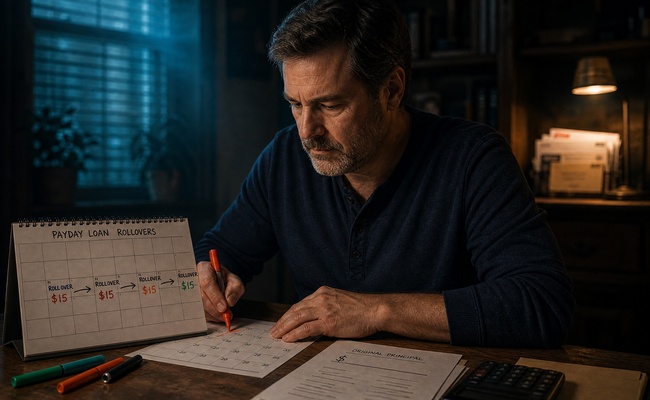
For example, a $500 loan with a $75 fee may require $575 after two weeks. If the borrower cannot pay the principal, another $75 may extend the arrangement without reducing the balance. Fees, renewal rules, and legal limits vary by lender and state, so the written agreement matters most.
Why Payday Loans Become Difficult So Quickly
Short repayment periods create the first pressure point in a payday loan debt trap. A person may borrow against income that is technically coming soon but already needed for recurring expenses. When the loan comes due, the borrower may have to choose between repaying the lender and paying a rent bill, utility account, insurance premium, or grocery expense. The loan did not remove the underlying shortage; it moved the shortage forward and added a financing cost.
Fees can create the second pressure point. The Federal Trade Commission’s debt guidance explains that payday lenders commonly charge a fee for each amount borrowed and that the annual percentage rate can be very high when that fee is converted to a yearly cost. Those costs are why a payday loan debt trap can grow even when every renewal fee is paid. The FTC also warns that rollovers can add new fees while the original balance remains outstanding. Use the lender’s written finance charge and APR to understand the actual cost rather than relying on the amount of the fee alone.
Automatic debits can create the third pressure point in a payday loan debt trap. If the agreement allows electronic withdrawals, a lender may attempt to collect when the account balance is low. A failed debit can trigger bank charges or leave less money for essential bills. Do not assume that simply ignoring the account will end the agreement, and do not make a sudden change to payment instructions without understanding the contract and getting qualified guidance when the consequences are serious.
Finally, urgency can narrow your choices. A new fee may feel easier than a difficult conversation with a creditor, credit union, employer, family member, community organization, or counselor. But the earlier you compare alternatives, the more options you may have. Your goal is to prevent one expensive short-term decision from becoming several expensive short-term decisions.
Five Proven Ways to Escape the Payday Loan Debt Trap
The best response to a payday loan debt trap depends on the due date, the amount owed, your next reliable income, and the bills that must be protected first. These five approaches are not promises or universal instructions. They are a sequence for evaluating what may be safer than another rollover.
1. Ask for a written extension or hardship arrangement. This is often the first step out of a payday loan debt trap. Contact the lender before the due date and explain what you can realistically pay. Ask whether an extended payment plan, revised due date, reduced payment, or other hardship option exists. Request the terms in writing, including the new total cost, fees, payment dates, and what happens if you miss a payment. A lender may refuse, but asking early is usually more useful than waiting until the account is already in default.
2. Replace the high-cost obligation only if the new terms are truly safer. When escaping a payday loan debt trap, compare the total repayment amount, fees, and consequences of late payment. A credit union small-dollar loan, employer advance, or community resource may be safer than repeated payday fees only if it ends the cycle and fits a sustainable budget.
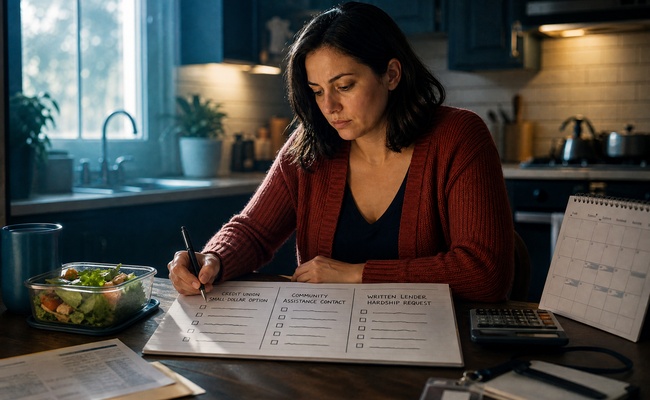
3. Build a bare-bones repayment plan. List the payday balance, fee, due date, and every essential expense. Then calculate what remains from your next paycheck after housing, utilities, food, transportation, insurance, and other obligations. A realistic debt repayment budget can help you see whether a payday loan debt trap can be ended without creating another emergency. If the numbers do not work, that is important information, not a personal failure.
4. Ask for help before using another rollover. A nonprofit counselor, local assistance organization, employer resource, credit union, or trusted support person may help you compare options. A counselor should review your finances before recommending a program and should explain how a payday loan debt trap fits, or does not fit, the costs and alternatives clearly. A debt management plan is generally designed for qualifying unsecured debts and may not solve a payday loan or every short-term obligation, so ask exactly what the service covers.
5. Document the agreement and prepare for collection contact. Save the original contract, payment history, account statements, debit notices, emails, and every conversation. If the account is transferred to a third party, the process and your rights may differ from the original lender relationship. The debt validation letter template can help you organize a written request when a third party collector contacts you about a payday loan debt trap you do not recognize or believe is inaccurate. A request does not automatically erase a valid debt or stop every legal deadline.
What to Do Before the Next Payment Is Due
Start by reading the agreement from beginning to end when a payday loan debt trap is still new. Identify the amount borrowed, finance charge, APR, due date, renewal provisions, electronic debit authorization, late fees, returned-payment fees, and any notice requirements. Write the figures on one page so you can compare the loan with every alternative. If you cannot understand a provision, mark it and ask a qualified consumer counselor or attorney rather than relying on a sales representative’s explanation.
Next, protect the bills that keep your household functioning before paying a payday loan debt trap at the expense of essentials. Housing, utilities, food, transportation, insurance, medication, and taxes deserve attention before an unsecured payday balance. That does not mean ignoring the lender. It means understanding the consequences of every payment decision and avoiding a plan that pays the payday fee today while creating a utility shutoff, missed rent, or transportation crisis tomorrow.
Call the lender and ask specific questions before a payday loan debt trap reaches another due date: Can the due date change? Is an extended payment plan available? What is the total amount required under the new arrangement? Will interest or fees continue? How will payments be applied? Will the lender attempt an electronic debit? Ask for the answers in writing. Keep the date, time, representative’s name, and any confirmation number in your records.
If the lender offers a new arrangement, compare it with the cost of doing nothing, paying the original amount, using a safer alternative, or seeking assistance. Do not sign a new agreement while rushing through a phone call. A lower payment can still be more expensive if it extends the debt for months. The right comparison is the full cost and the risk to your essential finances, not merely whether the payday loan debt trap disappears from this week’s account.
How to Compare Safer Alternatives
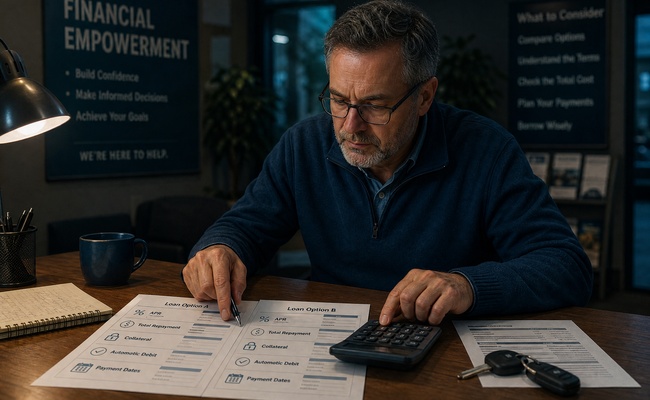
A safer alternative to a payday loan debt trap is not simply any loan with a lower advertised rate. Compare the amount you will receive, the total amount you will repay, the due dates, the fees, the consequences of late payment, and whether property or a bank account is placed at risk. The alternative should address the cash-flow problem without creating a larger or longer obligation that you cannot sustain.
A credit union or community lender may offer different underwriting and repayment terms, but approval is not guaranteed. The alternative must end the payday loan debt trap without creating a larger obligation. Ask for the APR, total cost, collateral, automatic debit terms, and payment schedule in writing.
Direct creditor negotiation may be part of a payday loan debt trap exit plan when another bill is causing the shortfall. A creditor may offer a hardship plan, lower rate, payment extension, or fee adjustment. The credit card hardship programs guide offers preparation principles for organizing income, expenses, and questions before a hardship call.
Debt consolidation may not be the right tool for a single payday balance, especially if the new loan has fees or collateral. Read the debt consolidation pros and cons before assuming one payment is safer. The new loan should reduce risk, not hide the payday loan debt trap inside a longer schedule.
What If You Cannot Repay the Loan on Time?
Do not wait until the due date has passed to learn what happens next in a payday loan debt trap. Review the agreement and contact the lender as early as possible. Ask whether the lender has a state-specific extended payment option, whether a renewal is permitted, and what the full cost would be. Some lenders may have formal procedures, while others may not offer a workable arrangement. Your job is to gather the terms, not to assume that an offer is affordable because it postpones the due date.
If a debit fails, returned-payment charges or repeated attempts may follow. Keep records. If a withdrawal appears unauthorized or does not match the agreement, contact your bank promptly and ask what dispute procedures may apply.
If the account reaches collections, distinguish the original lender from a third party debt collector handling the payday loan debt trap. The Consumer Financial Protection Bureau’s debt collection consumer guidance explains that consumers can review information about validation notices, collector communications, harassment, judgments, garnishment, lawsuits, and complaints. A collector may still seek payment on a valid debt, but you should preserve the notices and respond carefully rather than making promises you cannot keep.
If a collector threatens legal action about the payday loan debt trap, do not ignore official court papers. A phone threat is not the same as a summons, and a complaint deadline can be controlled by state law. Gather the contract, payment history, notices, and account information. If you receive legal papers or believe the collector is using deceptive or abusive conduct, consider qualified legal help. The Fair Debt Collection Practices Act information describes federal limits on certain third party collection conduct, but it does not answer every state-law or contract question.
Warning Signs of a Payday Loan or Debt Relief Scam
Some people enter a payday loan debt trap while trying to avoid another financial emergency, and that urgency can make promises sound more convincing. The same urgency can make a payday loan debt trap scam easier to miss. Be cautious when a company guarantees approval, promises to erase every debt, claims it can stop all collection lawsuits, or refuses to explain the total cost in writing. A legitimate service should be able to describe what it does, how it is paid, what it cannot promise, and what happens if the plan fails.
Be especially careful with anyone who demands a large upfront fee, asks for sensitive information before identifying the debt, instructs you to stop communicating with everyone, or pressures you to sign immediately. Those tactics can deepen a payday loan debt trap. Our debt relief scam warning signs can help you make a checklist before giving a company money or access to an account. Search for complaints, verify licensing where applicable, and compare direct assistance with paid services.
Do not assume that a government reference makes a program legitimate. Scammers may use official-sounding names, fake seals, or urgent messages. A payday loan debt trap does not become safer because a company uses government-sounding language. Verify the organization through an official website or phone number that you find independently. Never share a bank password, full authentication code, or unrelated personal information with someone who contacted you unexpectedly about a payday loan.
Should You Use Debt Settlement to Pay a Payday Loan?
Debt settlement is usually discussed for unsecured debts a creditor may accept for less than the full balance. It is not an automatic solution to a payday loan debt trap. Do not assume a settlement company can negotiate every short-term loan or stop debits and collection activity.
Settlement programs can involve fees, saved funds, missed payments, credit damage, and collection risk. Those consequences can make a payday loan debt trap harder to resolve. Ask which debts qualify, when fees are charged, what happens if no agreement is reached, and whether you can leave without losing funds.
When the debt is unaffordable and collection pressure is escalating, a qualified consumer attorney or nonprofit counselor may help you understand your options for ending a payday loan debt trap. That does not mean you must file a lawsuit, declare bankruptcy, or hire a settlement company. It means you should make the next decision with complete information instead of allowing a rollover or sales promise to determine the outcome.
Your Seven-Day Payday Loan Exit Plan
Day one: Gather the loan agreement, payment history, bank records, notices, and every message from the lender. Start a payday loan debt trap file so nothing is lost. Write down the borrowed amount, fees, total due, due date, renewal terms, and debit authorization. If any item is missing, request a copy in writing.
Day two: Build a bare-bones budget that protects housing, utilities, food, transportation, insurance, medication, and taxes. Calculate what remains for the payday loan. If the available amount is less than the required payment, do not hide that fact from yourself; it tells you that another rollover may not solve the problem.
Day three: Contact the lender and ask about written hardship or extended payment terms. Ask for the total cost and payment schedule. Do not accept an arrangement you cannot complete simply because it delays the due date.
Day four: Compare safer help sources and record the full repayment amount and failure consequences on the same worksheet.
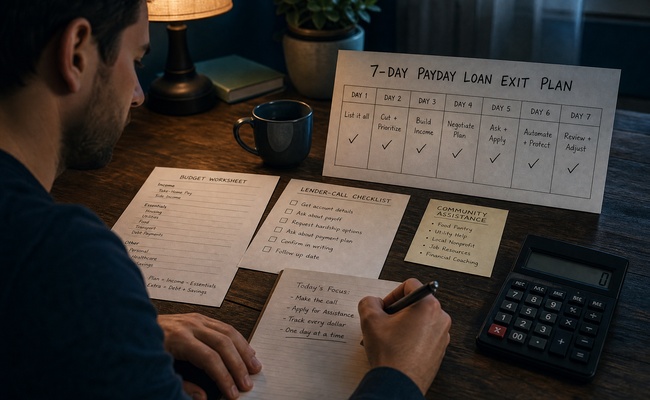
Day five: Document every debit attempt and save each collection notice. Do not ignore official legal papers.
Day six: Review the proposed agreement, budget, and risks with a qualified professional when the decision could affect your wages, vehicle, housing, or legal rights. Be cautious of services that charge before explaining the work or promise results no one can guarantee.
Day seven: Choose the next sustainable action and write down the date you will reassess it. A successful exit is not the most dramatic promise; it is a plan that reduces the cycle without sacrificing essential household needs.
Frequently Asked Questions
What is a payday loan debt trap?
A payday loan debt trap occurs when a short-term loan cannot be repaid from the next paycheck after essential expenses are covered. The borrower may pay repeated fees or renewals while the original principal remains, making each pay period harder to manage.
How can I get out of a payday loan debt trap without another loan?
Start by calculating essential expenses and the amount you can realistically pay. Ask the lender about written hardship terms, seek nonprofit or community assistance, and compare a repayment plan with safer alternatives. Do not assume that a new loan is the only answer.
Should I roll over my payday loan when I am in a payday loan debt trap?
A rollover may delay the due date, but it can add another fee while leaving the original balance outstanding. Review the total cost and compare it with a written extension, repayment arrangement, or qualified assistance before agreeing.
Can a payday lender take money from my bank account?
The answer depends on the authorization, account records, contract, and applicable law. Review the debit terms, keep documentation, and contact your bank promptly if a withdrawal appears unauthorized or does not match the agreement. Do not assume that closing an account or stopping a payment resolves the underlying debt.
What should I do if a debt collector contacts me about the loan?
Preserve the notice, identify who is contacting you, and review whether the amount and account are accurate. Ask for information in writing when appropriate and do not promise a payment you cannot make. If you receive court papers or believe the conduct is unlawful, seek qualified legal help promptly.
Are payday loans illegal?
Payday lending rules vary by state. Some states restrict or prohibit certain high-cost short-term loans, while others permit them with limits and disclosures. Review the agreement and check current state guidance rather than assuming the same rule applies everywhere.
Here Are More Articles That Might Interest You
Use the priority debt checklist to protect essential obligations before deciding how to handle unsecured balances.
Learn how to use a debt payoff calculator to compare timelines and payment amounts.
See how to negotiate a lower credit card interest rate when high interest is contributing to the cash-flow shortage.
Compare credit counseling versus debt settlement before paying for a debt-relief service.
Understand secured versus unsecured debt and why collateral changes the consequences of nonpayment.
Review whether using an emergency fund to pay off debt could leave you vulnerable to the next unexpected expense.
Start with Drowning in Debt? Here Is What to Do First when several financial problems are happening at once.
Compare balance transfer strategies and their fees before moving credit card balances.
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.