Monique grips the top of her open car door and looks across the rain-darkened parking lot toward a tow truck. Her worry is bigger than a payment: if borrowing against the car puts it at risk, how will she manage without it?
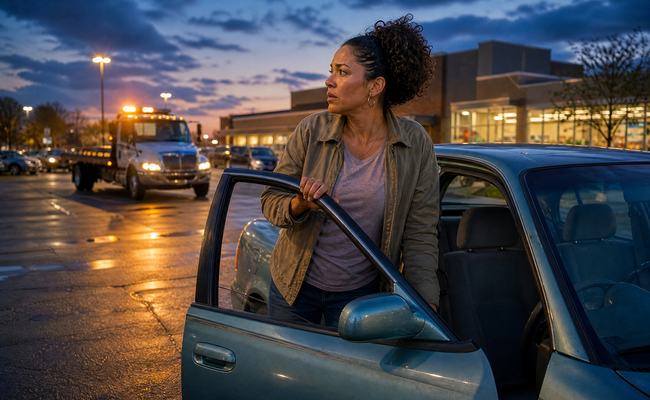
The truck’s presence does not tell us what will happen to her car. But Monique’s concern captures the decision a title loan creates: solving an urgent cash shortage can put essential transportation on the line. How do these loans work, what can go wrong, and which alternatives should you check first?
The Debt Survival Guide is led by Jim Prather, a retired CPA with 45 years of experience. Articles are created with AI assistance through a structured research and writing process. Jim provides editorial direction and performs a high-level structural review, but he does not personally write or line-edit every article. Important legal details should be verified through the cited official sources or a qualified professional.
Table of Contents
How a Car Title Loan Works
Short answer: A car title loan uses your vehicle title as collateral. Short repayment terms and high fees can make the balance difficult to repay, and default can put the vehicle at risk of repossession. Before signing, compare the full repayment amount with your available income and check alternatives that do not pledge your car.
The FTC’s payday and car title loan guidance describes title loans as short-term loans, often lasting 15 or 30 days. The lender generally holds the title while you continue using the vehicle. Your agreement may have a different repayment schedule, so do not treat those common terms as a promise about a particular offer.
The lender may require an application, your vehicle, title, identification, and other information. The FTC notes that some lenders also require an extra set of keys or roadside-service membership. Ask what is required and what each item costs before agreeing.
The central question is not simply how much you can borrow. It is whether you can repay the full obligation by the required date without another loan or extension. Our secured versus unsecured debt guide explains why pledging property changes the consequences of falling behind.
Fees, APR, and Rollover Costs
Compare the cash you receive with the total amount needed to repay the loan. A finance charge may be accompanied by processing, document, origination, or other fees. The annual percentage rate, or APR, expresses borrowing cost on an annual basis and helps you compare offers with different terms. A fee quoted for one month is not the same as an annual rate.
As an illustration, the FTC describes a $1,000 title loan with a 25% monthly finance fee. The fee is $250, so repayment after 30 days would be $1,250; the FTC describes the APR as about 300%. These are the FTC’s example figures, not a prediction of every lender’s pricing or a statement that those terms are permitted everywhere.
If you cannot repay, a lender may offer a rollover where permitted. In the FTC’s example, paying the $250 fee to extend the loan does not reduce the $1,000 principal. Another $250 fee becomes due for the next period. You have bought time, not paid down the original borrowing.
Before accepting an extension, ask for the new due date, added charges, remaining principal, and total payoff in writing. Use a realistic debt repayment budget to test whether the next payment fits after essentials. If repayment depends on another rollover, the extension may postpone rather than solve the shortage.
Repossession and What May Happen After a Sale
The FTC warns that a lender may take your vehicle if you cannot repay a title loan. Whether and when repossession is allowed, what notices are required, and whether you have an opportunity to catch up depend on applicable law and the agreement. Do not assume that a partial payment automatically prevents repossession or that every missed payment has the same consequence nationwide.
A repossessed vehicle may be sold. Depending on local law and the contract, sale proceeds may not eliminate the entire obligation: a remaining balance, sometimes called a deficiency, or additional charges may be an issue. Other rules may govern any surplus proceeds. The FTC specifically cautions that a lender may not have to return money left after selling the car and paying the debt. Get qualified local legal help to determine which rules apply; neither a national article nor a lender’s verbal assurance resolves that question.
Include the practical cost of losing transportation in your comparison. Price the rides or transit you would need for essential trips, and consider whether losing access to the car would disrupt income or caregiving. Those costs do not appear in the loan’s APR, but they belong in your decision.
What to Check Before Signing
Request a complete written agreement and take time to review it. Ask for written explanations of terms you do not understand, especially anything involving default, extensions, repossession, or sale.
- Record the cash received, finance charge, APR, all additional fees, and total repayment.
- Confirm each due date and whether repayment is a lump sum or installments.
- Check whether an extension is available, what it costs, and whether any payment reduces principal.
- Identify the vehicle pledged, any title or key requirements, and any account-debit authorization.
- Read the default, notice, repossession, sale, and remaining-balance provisions.
- Verify current state rules and any applicable licensing requirements through your state financial regulator or attorney general’s office.
The CFPB’s guidance on checking payday-lender licensing points consumers to state regulators and attorneys general. That page concerns payday lending, not a determination of title-loan legality. Use those official offices to ask specifically about the title-loan product and lender you are considering.
The CFPB’s auto-loan resources can also help you organize questions about rates, terms, and total cost when comparing vehicle-related borrowing. A vehicle-purchase loan is different from a short-term title loan; do not assume its terms or protections apply to your title-loan agreement.
Safer Alternatives to Check First
Start with the bill or emergency that created the shortage. The FTC recommends asking creditors for more time and comparing less costly borrowing options. A payment arrangement may avoid pledging your vehicle, but ask about added interest, fees, and consequences before accepting it.
- First, ask the creditor or bill provider about an extension, installments, or a hardship arrangement. Request the terms in writing.
- Next, check a credit union or bank for a small loan. Compare APR, total cost, collateral, payment dates, and default consequences; approval and favorable terms are not guaranteed.
- Ask whether an employer offers a pay advance, and check what will be deducted from later paychecks.
- Consider available savings or a family loan only after assessing the effect on essential expenses and relationships. Put any family repayment agreement in writing.
- If the shortage is recurring, ask a reputable credit counselor to review the budget and options. Check fees before agreeing to services.
Our emergency fund decision guide offers questions to consider before using reserves. If several bills are competing for limited cash, use the priority debt checklist to map essential needs and payment consequences rather than paying whichever creditor applies the most pressure.
A different loan is not automatically safer. The useful comparison is total cost, realistic repayment, and what happens if the plan fails. An option that does not pledge the car may remove one major risk while still creating fees or an unaffordable payment.
If You Already Have a Title Loan
First, gather the contract, payment receipts, lender messages, account records, and all notices. Write down the original cash received, fees already paid, remaining principal, next due date, and rollover history. Request a current written payoff quote if the balance is unclear.
Next, contact the lender promptly about any repayment arrangement it may offer. Ask whether payments reduce principal, whether additional fees apply, and how the arrangement affects default or repossession. Get the terms in writing before relying on them. An extension is not necessarily a reduction in debt.
If repayment still does not fit, compare alternatives and seek qualified help rather than assuming another rollover will fix the problem. A credit counselor can help review affordability; a consumer attorney or legal-aid organization is better placed to assess local-law questions about repossession, notices, and sale consequences.
If you receive repossession-related notices or court papers, save them and seek legal help promptly. Do not delay because of a general review checklist. Note any stated deadlines and ask what they mean for your situation. Keep a record of calls and copies of written communications.
Common Questions About Title Loans
Are title loans legal everywhere?
No nationwide answer establishes whether a particular offer is lawful. State rules differ. Verify current requirements with the appropriate state regulator or attorney general’s office, and consult qualified local counsel if the contract or lender’s authority is disputed.
Does paying the extension fee pay down the loan?
Not necessarily. In the FTC’s illustration, the extension fee leaves the original principal unpaid. Ask the lender to show exactly how a proposed payment will be allocated and what balance will remain afterward.
Does losing the car mean the debt is finished?
Do not assume so. The handling of sale proceeds, fees, any deficiency, and any surplus depends on applicable law and the agreement. Request a written accounting and get qualified local help if you cannot reconcile it or dispute the sale process.
What to Do Next
Before signing or rolling over a title loan, put three figures on one page: the cash you need, the full repayment amount, and the money actually available by the due date after essentials. Then ask the bill provider for an arrangement and compare another available option. If neither route works, seek counseling or qualified local legal help rather than treating approval as proof that borrowing is affordable.
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. this article explains general title-loan risks and is not a local-law determination or individualized borrowing recommendation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.