Monica sat at her dining-room table with six envelopes spread in front of her and three browser tabs open on her laptop. One tab described a debt management plan. Another promised to settle her credit cards for less than she owed. The third advertised a consolidation loan with a payment that looked almost too good to be true. Her checking account could not support all of them, and every company seemed certain that its solution was the one she needed. Monica did not need another sales pitch. She needed to understand her debt relief options before choosing a path that could affect her budget, credit, taxes, and financial future.
She wrote the question at the top of a notebook: Which debt relief options actually fit my situation? The answer would depend on whether she could still afford her minimum payments, how stable her income was, whether any debt was secured by property, and how quickly collection pressure was escalating. Comparing debt relief options carefully would help Monica avoid making a desperate decision based only on a lower advertised monthly payment.
At The Debt Survival Guide, our team draws on over 45 years of CPA experience to help people evaluate difficult financial decisions with clarity and caution. We understand that debt relief options are not interchangeable products and that the lowest monthly payment is not always the least expensive or safest path. A useful comparison must examine what each option changes, what it leaves untouched, how it affects credit and collection risk, what it costs, and what a person must do to complete the process successfully.
Table of Contents
What Are the Best Debt Relief Options?
There is no single best choice for everyone. The most appropriate debt relief options depend on your income, debt types, payment history, interest rates, assets, household expenses, and ability to make a reliable monthly payment. Someone who can afford a reduced payment may benefit from nonprofit counseling or a repayment plan, while someone who cannot realistically repay unsecured debt may need to discuss bankruptcy with a qualified attorney. A person with stable income and manageable balances may be able to solve the problem without hiring a company at all.
The safest starting point is to identify the actual problem. If high interest is the main issue, reducing the rate or changing the repayment method may help. If the monthly payment is unaffordable, extending the term or negotiating hardship terms may be more important. If collection lawsuits or secured debts threaten your housing, transportation, or wages, the situation requires urgent individualized attention. The Federal Trade Commission’s debt guidance recommends beginning with a realistic assessment and contacting creditors or legitimate counselors before paying a company for promises you may be able to pursue yourself.
Before comparing debt relief options, separate secured debts from unsecured debts. A mortgage or auto loan is tied to collateral, while many credit cards, medical bills, and personal loans are unsecured. A plan that helps with credit card balances may not protect a home or vehicle from foreclosure or repossession. Also flag federal student loans, tax debts, child support, and accounts involved in a lawsuit because those obligations can have different rules and consequences.
Debt Relief Options at a Glance
Do-it-yourself repayment: Among the debt relief options, this approach may fit someone with steady income who can cover essential expenses and minimum payments while directing extra money toward one target balance. You keep control and usually avoid program fees, but success depends on having enough monthly cash flow and a workable plan. A realistic debt repayment budget can show whether this path is actually affordable.
Direct hardship negotiation: Among the debt relief options, direct creditor negotiation lets you request a lower interest rate, temporary payment reduction, fee waiver, or modified schedule. This can be useful when a short-term income interruption created the problem. It does not guarantee approval, and any new agreement should be reviewed carefully and saved in writing.
Nonprofit credit counseling or a debt management plan: Among the debt relief options, a counselor may help build a budget and arrange one monthly payment for qualifying unsecured debts. The debt usually remains yours, but interest rates or fees may be reduced in some programs when creditors participate and written terms provide for it. This option may suit a person who can repay the principal but needs structure or more manageable terms.
Debt consolidation loan: Among the debt relief options, a new loan pays off multiple debts and leaves you with one payment. It may simplify repayment and reduce interest, but fees, variable rates, longer terms, and collateral can change the result. Consolidation only helps if the new terms are genuinely better and you do not rebuild the balances afterward.
Debt settlement: Among the debt relief options, a company or the consumer negotiates to resolve a debt for less than the full balance. The process can involve fees, missed payments, collection activity, lawsuits, credit damage, and possible tax consequences. It may be considered only after understanding the risks and verifying the terms, not because an advertisement promises a guaranteed percentage reduction.
Bankruptcy: Among the debt relief options, bankruptcy is a federal legal process that may discharge certain debts or create a court-approved repayment structure. It can provide powerful relief, but eligibility, exemptions, costs, and consequences depend on the individual case. It should be discussed with a qualified bankruptcy attorney rather than treated as a casual online program.
Do-It-Yourself Repayment and Direct Creditor Help
The least complicated of the debt relief options is often the one people overlook: creating a written plan and contacting creditors directly. Begin by listing each debt, balance, interest rate, minimum payment, due date, and consequence of nonpayment. Then calculate the amount left after housing, utilities, food, transportation, insurance, taxes, and other essential expenses. If the remaining amount is positive, you may be able to direct extra money toward one balance while keeping the others current.
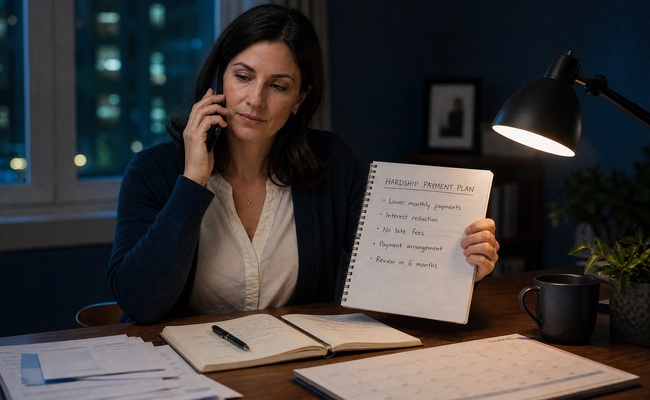
Among the debt relief options, direct creditor help is the fastest place to start when possible. Contact a creditor before the account becomes seriously delinquent. Explain the income or expense change, ask what hardship programs are available, and request the terms in writing. A temporary rate reduction or payment arrangement can be valuable, but check whether interest continues to accumulate, whether the account is closed, and whether the agreement changes your credit reporting. Do not assume that a verbal promise from a call-center representative is a permanent modification.
Nonprofit Credit Counseling and Debt Management Plans
Nonprofit credit counseling is one of the debt relief options for people who need education, budgeting help, and a structured repayment plan. A counselor should review your complete financial situation before recommending a program. The goal is usually to make repayment more manageable, not to erase the principal. A debt management plan may combine qualifying unsecured accounts into one monthly payment that the counseling organization distributes to creditors.
A debt management plan may reduce interest rates or waive certain fees, but it does not automatically make every debt eligible. Mortgages, car loans, tax obligations, and some student loans may be outside the plan. You may also be asked to stop using enrolled credit cards while the plan is active. Ask about enrollment fees, monthly fees, creditor participation, the estimated completion date, and what happens if you miss a payment.
One of the most important distinctions among debt relief options is that a debt management plan generally organizes repayment rather than negotiating away the balance. The debt management plan guide can help you understand the structure, but you should still compare the organization’s written terms with your budget. A plan is only useful if the monthly payment is sustainable for the entire period.
Ask a counseling organization whether it provides free educational materials, gives you time to review the contract, and explains alternatives when its recommended plan is not affordable. Be cautious of anyone who promises to fix every financial problem, demands payment before explaining the service, or says one program is the only answer. Nonprofit status alone does not guarantee that a service is free, suitable, or well managed. Counseling is usually best for someone who can repay unsecured debt but needs a lower rate, organized payments, and accountability.
Debt Consolidation Loans and Balance Transfers
Among the debt relief options, debt consolidation replaces several payments with one new loan. The idea can be appealing because one due date is easier to manage and the new interest rate may be lower than the rates on credit cards. However, consolidation does not automatically reduce what you owe. It transfers the balance into a different contract, and the result depends on the rate, term, fees, collateral, and your behavior after the old accounts are paid.
Calculate the total repayment amount before comparing this option with other debt relief options. A loan with a lower monthly payment may stretch repayment for many additional years. An introductory rate may expire, an origination fee may reduce the savings, or a loan secured by your home may turn unsecured credit card debt into a threat to your property. Use the full-term cost, not the first advertised payment, as the basis for the decision.
Debt Settlement: Possible Savings With Serious Risks
Debt settlement is often marketed as one of the fastest debt relief options because the company promises to negotiate a reduced payoff. In reality, settlement depends on whether each creditor agrees, how much money you can save, how long the negotiations take, and whether you can tolerate collection activity while funds accumulate. No settlement company can guarantee that every debt will be reduced or that the process will finish on a particular date.
Some settlement programs may instruct consumers to stop paying creditors and place money into a dedicated account. That strategy can allow funds to accumulate, but it can also add late fees and interest, damage credit, increase collection calls, and create the possibility of a lawsuit. If a creditor sues before a settlement is reached, the program may not protect you. The CFPB’s debt-collection consumer guidance explains why consumers should understand their rights and respond carefully when collectors contact them.
Fees deserve close attention. Ask when the company may charge, whether fees are based on enrolled debt or savings, what happens if you leave the program, and whether the dedicated account is independent and under your control. Never rely on a verbal promise that a company can settle every account for pennies on the dollar. Get the settlement offer from the creditor in writing before authorizing payment, and keep records of the original balance, negotiated amount, fees, and final resolution.
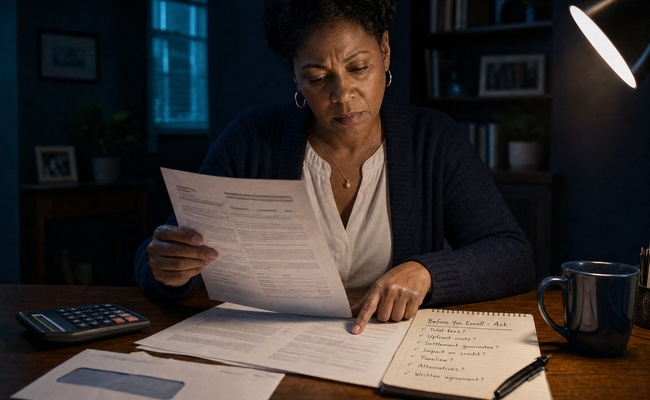
Debt settlement may also create tax questions if a creditor forgives part of a balance. The amount treated as income can depend on the facts and applicable exceptions, so consult a qualified tax professional before assuming that a forgiven balance is tax-free. The taxes on settled debt guide provides additional background, but it cannot replace advice about your tax return.
Walk away from any provider that guarantees results, claims a new government program will erase your credit card debt, demands large fees before doing the work, tells you to stop communicating with creditors, or promises to stop every lawsuit. The Federal Trade Commission’s Fair Debt Collection Practices Act information is useful for understanding federal protections, but protections do not make a risky settlement strategy safe or successful.
Settlement may be considered only after comparing the full downside with the potential benefit and confirming that the debts are appropriate for negotiation. It is generally not the first choice for secured debts, current accounts that you can afford, or obligations where stopping payments could cause immediate harm. If you cannot afford any sustainable repayment, bankruptcy may deserve an honest legal comparison instead of assuming settlement is automatically less serious.
Bankruptcy as a Legal Debt Relief Option
Bankruptcy is the most formal among the debt relief options because it uses a federal court process to address qualifying debts and assets. It can provide a fresh start in circumstances where income, debt, and collection pressure make ordinary repayment unrealistic. Bankruptcy is not a moral failure, but it is not a simple debt-relief subscription either. The outcome can depend on household income, assets, exemptions, debt types, prior filings, and the chapter involved.
Chapter 7 generally involves a liquidation framework, while Chapter 13 generally involves a court-supervised repayment plan for eligible individuals with regular income. These are broad descriptions, not personalized legal advice. Some debts may not be discharged, liens may continue to affect collateral, and state-specific exemptions can change the practical result. A consultation with a qualified bankruptcy attorney is essential before making a filing decision.
Bankruptcy can stop or slow certain collection actions through the automatic stay, but the timing and exceptions matter. It may affect credit access, housing applications, insurance decisions, employment screening in some contexts, and future borrowing, but any practical effect depends on the type of screening, jurisdiction, provider, and applicable law. Those consequences should be weighed against the damage and legal exposure that may continue if unaffordable debt is left unresolved. The bankruptcy versus debt settlement comparison can help organize the questions to take to an attorney.
Do not compare bankruptcy only with the most optimistic version of settlement or the most frightening version of filing. Compare realistic costs, lawsuit risk, missed-payment effects, protected assets, completion time, and the likelihood that you can finish each path. Bankruptcy may be reasonable for one household and inappropriate for another even when the debt totals look similar. If a foreclosure sale, repossession, garnishment, or lawsuit deadline is near, gather your records and speak with a qualified professional promptly.
How to Choose Among Debt Relief Options
Start with your monthly cash flow, not with the company that has the most persuasive advertisement. Add your reliable after-tax income, subtract essential expenses, and determine what remains for debt payments. Then classify each account as secured or unsecured and mark any account that is in collections, charge-off, lawsuit, or other legal escalation. This first pass tells you whether the problem is primarily interest, organization, cash flow, or an inability to repay.
Ask these questions of every provider offering debt relief options: What exactly will you do? Which debts qualify? How are you paid? When can you charge me? What happens if a creditor refuses? Will you tell me to stop paying? What are the effects on credit, taxes, and lawsuits? Can I cancel? Can I review the contract before paying? A trustworthy provider should answer clearly and allow time for comparison. Start your debt relief options review with the full cost, not only the monthly payment.
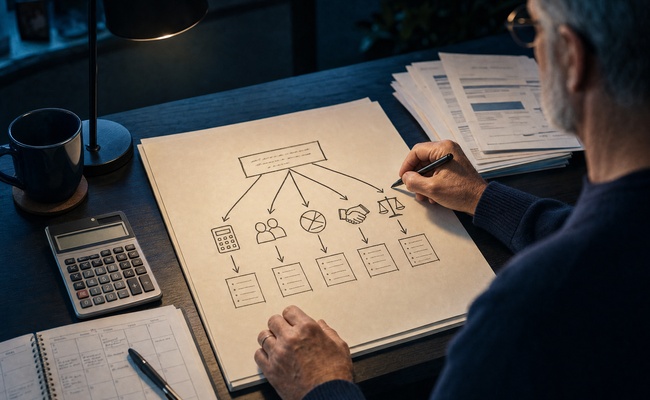
Use caution with testimonials that show a dramatic balance reduction without revealing fees, missed payments, taxes, lawsuits, or completion rates. A monthly payment is only one data point. Total cost, completion likelihood, legal exposure, and failure consequences matter just as much. The best debt relief options are the ones whose risks you understand and whose requirements you can realistically meet.
Finally, avoid trying to solve every debt at once with a new loan or program. Good debt relief options protect housing, utilities, food, transportation, insurance, taxes, and other essential obligations first. Then address unsecured debt with a method that preserves enough cash for emergencies. The emergency-fund comparison explains why using every available dollar for debt can leave you vulnerable to the next repair or income interruption.
Your Seven-Day Debt Relief Action Plan
On day one, gather the records you need to compare debt relief options: statements, collection letters, loan contracts, tax notices, and recent income records. Write down each balance, rate, minimum payment, due date, collateral, and current status. Do not estimate from memory. A complete list prevents an advertisement or collector from defining the entire picture for you.
On day two, build a bare-bones budget that protects essential living costs. On day three, identify which accounts require immediate contact because of a missed payment, lawsuit, foreclosure, repossession, or utility risk. On day four, call creditors or a reputable counselor and ask for written hardship or repayment options. Keep a log of every conversation, name, date, promise, and next step.
On day five, compare at least two debt relief options using the same criteria: total cost, monthly payment, length, fees, credit effects, tax issues, legal risk, and what happens if the plan fails. On day six, review any contract with a qualified professional when the stakes are high. On day seven, choose the next action you can sustain, not the most dramatic promise you have seen online. A debt relief options comparison should also account for what happens if the plan fails.
Revisit debt relief options monthly. A new lawsuit, income change, medical event, or interest-rate adjustment can change the comparison. Do not keep making payments to a program that no longer fits without asking what alternatives exist. Debt relief options are tools, not permanent identities; the correct choice can change as your circumstances change.
Frequently Asked Questions
How should I compare debt relief options?
There is no universal best option. A person with stable income and high-interest unsecured debt may start with a budget, direct negotiation, or nonprofit counseling. Someone who cannot afford a sustainable repayment plan may need to compare settlement risks with bankruptcy advice. The best choice is the one that addresses the actual problem and can be completed safely.
Can debt relief options reduce the amount I owe?
Some options may reduce interest, fees, or the balance accepted in a settlement, but a debt management plan generally organizes repayment rather than erasing principal. Consolidation replaces debts with a new loan. Bankruptcy may discharge qualifying debts under a court process. Read the exact terms and do not treat advertising claims as guarantees.
Will debt relief options hurt my credit?
The effect depends on the option and your payment history. A new loan may create an inquiry, while missed payments or settlement negotiations can damage credit. A completed plan and consistently paid accounts may support recovery over time. Ask for a written explanation of expected reporting before enrolling.
Should I stop paying my creditors if I use debt settlement?
Do not stop payments simply because a company tells you to. Stopping can add fees and interest, damage credit, increase collection activity, and create lawsuit risk. Understand the consequences, review the contract, and seek qualified advice before making a decision that could be difficult to reverse.
When should I consider bankruptcy?
Consider speaking with a bankruptcy attorney when you cannot cover essential expenses and minimum payments, face lawsuits or garnishment, or see no realistic way to repay unsecured debt. A consultation does not require you to file. It can help you compare the legal process with the long-term cost and risk of continuing without a workable plan.
Are debt relief companies required to tell me their fees?
Providers should explain their fees, timing, services, cancellation terms, and possible consequences before you commit. Be especially cautious when a company demands upfront settlement fees, guarantees that every debt will disappear, or refuses to provide written terms. Compare the provider with nonprofit counseling and direct creditor negotiation first.
Here Are More Articles That Might Interest You
Learn how the minimum payment trap can keep balances growing even when every payment is made on time.
See whether using a 401(k) to pay off debt creates more risk than relief for your long-term financial security.
Understand what happens to debt after the death of a spouse or family member in Debt After Death.
Review how the statute of limitations on debt by state can affect collection lawsuits and old accounts.
Learn how credit utilization impacts your credit score while you work toward lower balances.
Explore balance transfer strategies and the costs to evaluate before moving a credit card balance.
Find out what can happen when you stop paying credit cards and how to prepare for possible collection activity.
Read Drowning in Debt? Here Is What to Do First for a practical starting framework when every bill feels urgent.
Understand what it means to be judgment proof and why income and assets matter when collectors pursue a judgment.
Sources & References
- Federal Trade Commission: Debt relief services
- Consumer Financial Protection Bureau: Debt collection guidance
- Internal Revenue Service: Canceled debt and Form 1099-C
- U.S. Department of Justice: Bankruptcy information
Join Our Newsletter
From time to time, we’ll send you information and resources that we believe may be helpful to you.
Subscribe to The Debt Survival Guide Newsletter
Disclaimer: The Debt Survival Guide provides educational content only. We are not attorneys, tax professionals, or financial advisors. This information should not be considered legal, tax, housing, credit, or individualized financial advice. Circumstances, agreements, deadlines, laws, and available options vary by person, account, location, and situation. Please review your records and written terms and consult a qualified attorney, legal-aid organization, HUD-approved housing counselor, tax professional, credit counselor, or financial professional before making decisions about your specific situation.